Business
Waters Outlines Agenda in First Policy Speech as Committee Chairwoman
NNPA NEWSWIRE — “…Millions of families that rely on HUD rental assistance programs are perilously close to losing their homes due to projected lapses in funding. What’s more, it was recently reported that HUD, under Secretary Carson’s leadership, has failed to follow its own contingency plan, and as a result 1,150 project-based rental assistance contracts have expired, with hundreds more hanging in the balance if this shutdown does not end.”
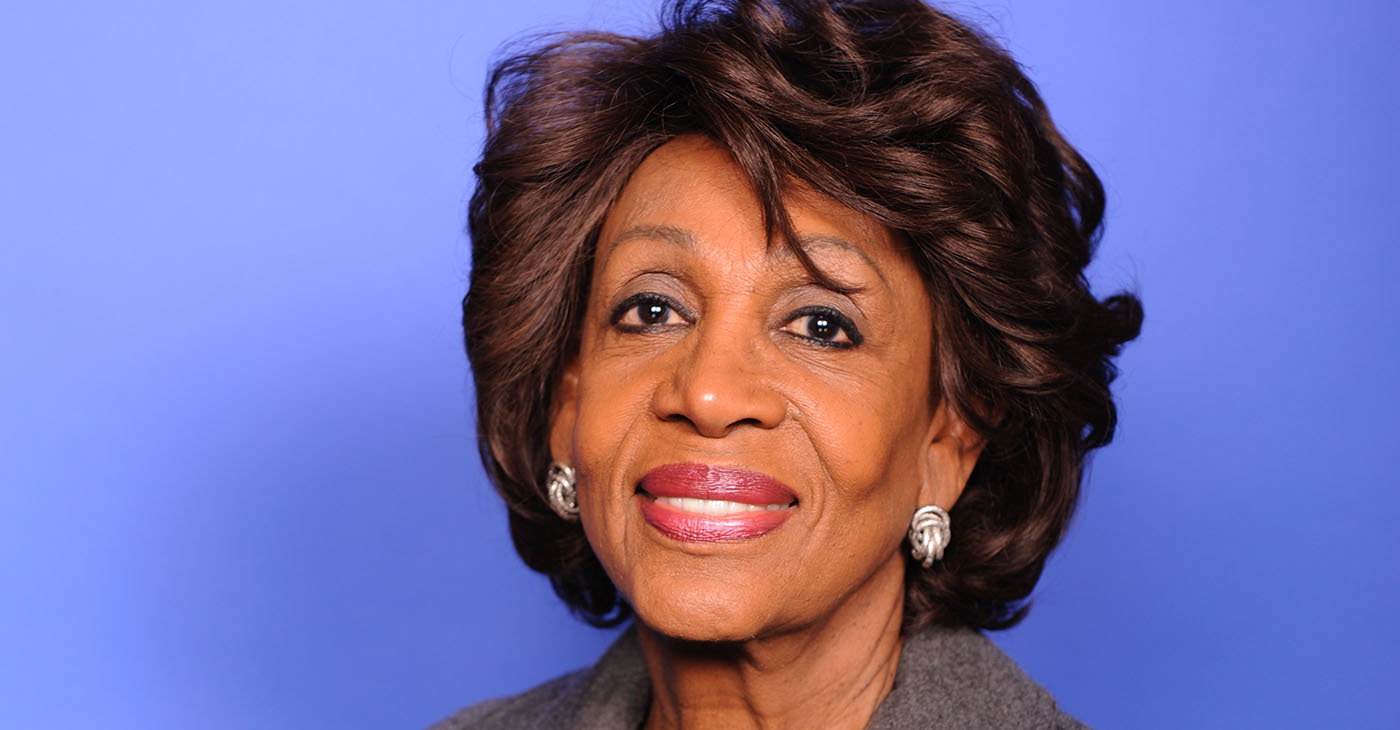
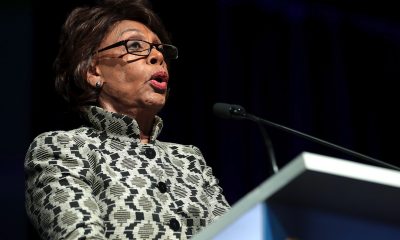
WASHINGTON — Congresswoman Maxine Waters (D-CA), Chairwoman of the House Committee on Financial Services, delivered the following remarks during her first policy speech in the 116th Congress:
As Prepared for Delivery
Thank you for the very warm welcome, and to the Center for American Progress for holding this event. CAP’s research and policy work are highly respected and a valued resource for Members of Congress and our staffs. I am very pleased to be here with you today to discuss the new Congress and my priorities as Chairwoman of the House Financial Services Committee.
I am deeply honored to have been selected by my colleagues to become the first woman and the first African American to serve as Chair of the Financial Services Committee. I have served on the Committee since 1991, and since 1995, I have served as Ranking Member or Chairwoman of every Subcommittee under the Committee’s jurisdiction, and have taken on important issues on behalf of consumers, investors, and vulnerable families.
So, I consider it a privilege to hold the gavel, and I am looking forward to working with my colleagues on the Committee on the many critical issues we are responsible for.
Trump Shutdown
Now, given the current circumstances in Washington, I would first like to address the shutdown and its impact on the important programs under the Financial Services Committee’s jurisdiction. We are now in the midst of the longest government shutdown in history – all because this President is throwing a tantrum about a senseless border wall.
The Trump shutdown is harming hardworking Americans and our financial markets. The shutdown has all but closed the doors of the Securities and Exchange Commission (SEC), which is Wall Street’s cop on the block. As a result of the shutdown, the SEC is unable to carry out most enforcement actions against bad actors. Businesses planning to enter the stock market for the first time through an Initial Public Offering (IPO) may also be delayed because the SEC cannot approve their documents, harming American entrepreneurs and job creation.
The shutdown also has a serious impact on critical housing programs. 95% of the Department of Housing and Urban Development’s staff has been furloughed. Millions of families that rely on HUD rental assistance programs are perilously close to losing their homes due to projected lapses in funding. What’s more, it was recently reported that HUD, under Secretary Carson’s leadership, has failed to follow its own contingency plan, and as a result 1,150 project-based rental assistance contracts have expired, with hundreds more hanging in the balance if this shutdown does not end.
Families aspiring to the American dream of homeownership may have their Federal Housing Administration (FHA) or rural housing loans delayed or be unable to close on their loans during the shutdown.
And in rural communities, very low-income, elderly homeowners who rely on HUD grants and loans to address health and safety hazards may not receive disbursements and as a result, may be forced to live in dangerous conditions.
These are just a few examples of the serious ways that this shutdown is harming American families and businesses. This shutdown must end immediately. I call on Republicans in Congress to join with us and put a stop to it and open the government so that we can put an end to all of the harm that this shutdown is causing.
The Consumer Financial Protection Bureau and Financial Regulation
An ongoing priority for me is ensuring that we have a strong Consumer Financial Protection Bureau and strong financial regulation that protects consumers, investors and our economy.
Let’s talk about why the Consumer Bureau is so important. We all remember how devastating the financial crisis was: 11 million Americans lost their homes, $13 trillion in wealth was lost, nearly 9 million Americans lost their jobs, and the unemployment rate hit 10 percent. It was catastrophic for communities across the country. The crisis was a result of Wall Street running amok, with abusive institutions peddling toxic products like no-doc loans, interest-only mortgages, and other predatory products, with no agency responsible for prioritizing consumer protection. Ultimately, the economy was sent tumbling into the abyss.
In response, Democrats crafted the Dodd-Frank Wall Street Reform and Consumer Protection Act, to improve accountability in the financial system and protect consumers, investors, and the economy from abusive Wall Street practices. As the centerpiece of that law, we created the Consumer Financial Protection Bureau, which is the only federal agency solely dedicated to protecting consumers from being ripped off by financial firms.
Under former Director Richard Cordray, the Consumer Bureau returned $12 billion to more than 30 million harmed consumers; handled over 1.3 million consumer complaints about financial institutions; implemented much needed rules on mortgages, prepaid cards, payday loans, and auto title loans; required clear disclosures from financial institutions; and, provided consumers with easy-to-understand materials to empower them to make the best decisions.
But Congressional Republicans and the Trump Administration have been determined to undermine and destroy the Consumer Bureau. Trump installed Mick Mulvaney, his budget director, to serve as Acting Director of the Consumer Bureau, and during his tenure, Mulvaney made it a priority to dismantle the Consumer Bureau from within. To name just a few of his actions, Mulvaney fired all members of the Consumer Advisory Board and requested zero dollars in operating funds for the Consumer Bureau from the Federal Reserve. He also created an Office of Cost Benefit Analysis as a way to internally block important regulations under the guise of cost benefit analysis.
He also moved to strip the Consumer Bureau’s Office of Fair Lending and Equal Opportunity of its enforcement and supervisory authority. But that’s not all. Mulvaney closed the Office of Students and Young Consumers at a time when 44 million student borrowers collectively carry over $1.5 trillion in student loan debt. He also helped out payday lenders. For example, he withdrew a lawsuit against a group of deceptive payday lenders who allegedly failed to disclose the true cost of loans, which carried interest rates as high as 950 percent a year.
Now, Kathy Kraninger was confirmed as the new Director in December, and we will see what she does. Mulvaney has since moved on to become this President’s Acting Chief of Staff. But I’ve written to Mr. Mulvaney to inform him that while his time running the Consumer Bureau may be over, the time for accountability for his actions is about to begin.
This Congress, I am going to be working diligently to undo the damage that Mulvaney has wrought during his time at the Consumer Bureau. I have a bill, the Consumers First Act, that reverses many of his known harmful actions, which I will soon be reintroducing.
But it’s not just Mick Mulvaney who I will be paying attention to. I will be keeping a watchful eye on all of the financial regulators to make sure that they are carrying out their statutory duties, including holding bad actors accountable, and promoting financial stability.
As we saw during the 2008 financial crisis, large Wall Street banks that aren’t subject to strong oversight and safeguards to protect our economy can do a lot of damage, and so in Dodd-Frank we put in place robust reforms for our largest and most complex financial institutions, including increased capital, reduced leverage, improved liquidity, vigorous stress testing, and thorough living wills, all designed to improve financial stability. Dodd-Frank established the Financial Stability Oversight Council to eliminate regulatory gaps and improve oversight of the entire financial system, including shadow banking. Dodd-Frank also established the Volcker Rule to ensure that big banks don’t gamble away their customers’ deposits. All of these reforms were designed to help prevent a future financial crisis. The Committee will be paying close attention to whether financial regulators try to weaken these important reforms, and keeping an eye on the big banks and their activities, including by holding many hearings.
Regulators also need to address the evolving financial marketplace appropriately. One emerging area the Financial Services Committee will be paying very close attention to is the growth of financial technology, or so-called “fintech” firms. As Americans are banking and accessing credit in new ways, it is important that we encourage responsible innovation with the appropriate safeguards in place to protect consumers and without displacing community banks and credit unions. I have great hopes that fintech firms can open up opportunities for those who have been excluded from access to responsible credit, but I strongly believe that there must be strong protections for consumers of these financial products, and that abusive payday lending practices must not be allowed. As the fintech sector grows, there are opportunities for unmet credit needs to be addressed, as well as risks that minority communities may be preyed upon or discriminated against by some of these companies. So we will be closely examining these issues in Committee to make sure that our regulators eliminate the risks, and meet the opportunities.
Credit reporting is another issue I will be scrutinizing. In the wake of the Equifax data breach, it’s absolutely critical for Congress to reform the nation’s credit reporting system. We need to shift the burden of removing mistakes from credit reports onto the credit bureaus and furnishers, and away from consumers. We also need to place limits on credit checks for employment purposes, reduce the time period that negative items stay on credit reports, and make other reforms to fix the serious problems with the credit reporting sector. For the sake of consumers across the country, credit reporting needs a comprehensive overhaul.
Housing
A very important issue we will be bringing renewed attention to in the Financial Services Committee is housing.
This country is experiencing a housing affordability and homelessness crisis. Today, there are over half a million people experiencing homelessness here in the richest country in the world, over one-fifth of whom are children. This includes veterans who we failed to support when they returned home after serving our country, women fleeing domestic violence, people who have left prison after serving their debt to society, and people who have simply fallen on hard times. It is simply shameful, and Congress has a responsibility to act.
To tackle the homelessness crisis, Congress needs to provide a surge of funding and resources. Just as Congress puts billions of dollars into defense spending, we must provide the funding necessary to ensure that all Americans have access to safe, decent and affordable housing.
So I will soon be reintroducing my bill, the Ending Homelessness Act, which would help to ensure that every American has a safe, decent, and affordable place to call home. The bill provides $13.27 billion in new funding over five years to federal programs and initiatives to prevent homelessness.
In addition, we will be holding Committee hearings on homelessness and important housing issues that have gone ignored during the last Congress, in order to elevate housing issues into a national discussion and present proactive solutions and remedies.
The Committee also has a responsibility to look at our housing finance system and address the fates of Fannie Mae and Freddie Mac, the government sponsored enterprises. The GSEs have been in government conservatorship for more than a decade.
Contrary to Republican claims, Fannie Mae and Freddie Mac did not cause the financial crisis. The Financial Crisis Inquiry Commission and others have made that clear. The financial crisis was driven by predatory lending, the private market packaging those toxic, risky loans into securities and then selling those securities to unsuspecting investors. Fannie and Freddie did not drive those actions, but the events that transpired during the crisis made clear the need for their reform. When it comes to housing finance reform, I have advocated for core principles that I believe should be part of legislative efforts to address the future of housing finance reform. The principles include:
- maintaining access to the 30-year fixed rate mortgage;
- ensuring sufficient private capital is in place to protect taxpayers;
- providing stability and liquidity so that we can withstand any future financial crisis;
- ensuring a smooth transition to a new finance system;
- requiring transparency and standardization in a way that ensures a level playing field for all financial institutions, especially credit unions and community banks;
- maintaining access for all qualified borrowers that can sustain homeownership and serving homeowners of the future; and
- ensuring access to affordable rental housing.
It is particularly important to ensure that underserved borrowers and communities are not overlooked. This means housing finance reform will need to include a comprehensive strategy around access to affordable mortgage credit, as well as access to affordable rental housing.
Also important for housing access is the rigorous enforcement of our fair housing laws. Unfortunately, our fight to make progress on fair housing has become much more challenging under the Trump Administration. Let’s not forget that President Trump himself was sued by the government for serious violations of the Fair Housing Act. Under Trump’s leadership, the affirmatively furthering fair housing mandate under the Fair Housing Act was badly undercut when Secretary Carson halted implementation of the Obama administration’s affirmatively furthering fair housing rule. In fact, Secretary Carson once likened the rule to a “failed social experiment.” Secretary Carson has also reportedly proposed taking the words “free from discrimination” out of HUD’s mission statement. He also reportedly halted several fair housing investigations, and sidelined top advisors in HUD’s Office of Fair Housing Enforcement. These are unprecedented attacks on fair housing that we will not stand for.
To that end, in addition to conducting robust oversight of the Trump Administration’s activities at HUD, I will be reintroducing the Restoring Fair Housing Protections Act, my bill to reverse the harmful steps taken by Secretary Carson and the Trump Administration to undermine fair housing. I promise to continue to stand up for fair housing opportunities for all people.
Diversity and Inclusion
Another very important issue that I am going to continue to work on as Chairwoman is diversity and inclusion. As a nation, we are becoming increasingly diverse, racially and ethnically. The U.S. Census Bureau estimates that more than half of all Americans will belong to a minority group by the year 2044. At the same time, there is a growing body of research showing a connection between the level of diversity at a company and the strength of its financial performance. Despite these facts, the Government Accountability Office (GAO) has found a continued trend of low representation of minorities and women in the financial services industry.
Minorities and women have particularly low representation at the senior management levels within the financial services industry. This needs to change. Diverse representation in these institutions, and particularly at the management level, is essential to ensure that all consumers have fair access to credit, capital and banking and financial services.
Now, as many of you know, I believe that it is essential to promote better workforce and supplier diversity. I am one of the proud authors of Section 1116 of the Housing and Economic Recovery Act and Section 342 of the Dodd-Frank Act. Together, these provisions direct most of the federal financial services agencies to create Offices of Minority and Women Inclusion, which we refer to as “OMWIs.” OMWIs have the important responsibility of overseeing all diversity matters in management, employment, and business activities at their agencies. The creation of these offices was a major step forward. But, we all know that laws that promote racial, ethnic, and gender equality are only as strong as the implementation and enforcement of those laws. And congressional oversight is essential to ensure that implementation and enforcement are strong.
So I am very pleased and very proud to announce that I will be creating a Subcommittee on Diversity and Inclusion. The Subcommittee will be the first in its kind in Congress, dedicated to looking at diversity and inclusion issues under the Committee’s jurisdiction.
International Affairs
Turning to the international jurisdiction of the Committee, I plan to focus on the important work of the World Bank and the regional development banks in ending global poverty. We have in the past worked in a bipartisan fashion to support the International Monetary Fund or IMF in times of crisis, at the same time that we pressed the Fund to pay more attention to the social dimension of problems when decisions about economic assistance are made. While the spirit of cooperation on issues related to global economic governance in Congress has been lacking, I am optimistic that this Congress will see renewed bipartisan attention.
Under my leadership, the Financial Services Committee will ensure that accountability and effectiveness at the international financial institutions remain strong, that broad public debate about the IMF’s and the multilateral development banks’ policies remains active, and that the international interests of poverty alleviation, growth, and economic stability continue to be advanced.
Sanctions
Another area that I hope will be bipartisan is the issue of protecting American interests and democratic institutions from assault both internally and from abroad. This brings me to the issue of U.S. sanctions against Russia for its hostile actions and its efforts to undermine the U.S. presidential election.
I believe the Administration’s approach to Russia sanctions has been haphazard and weak, as well as inconsistent with its approach to sanctions imposed on other countries, such as Iran.
I am very concerned about the Treasury Department’s recent actions to lift sanctions on businesses connected to Oleg Deripaska. Deripaska is a Russian oligarch with close ties to Vladimir Putin, who also has a history with Paul Manafort, former Trump campaign chairman who has been convicted of serious financial crimes uncovered as a result of Special Counsel Mueller’s investigation into Russian interference in the last presidential election.
What’s more, Deripaska has faced numerous allegations of criminal activity and was cited by the Treasury Department in April as saying he does not separate himself from the Russian state.
I believe the delisting agreement for Deripaska’s companies is too favorable to Deripaska, including by allowing him to benefit from potentially tens of millions of dollars in debt forgiveness by transferring some of his shares to a Russian bank to satisfy debts that Deripaska owes that bank. I also don’t believe Deripaska should be allowed to retain any influence or level of control over these companies.
I look forward to working with my colleagues in both chambers and across the aisle to closely monitor all further developments on Russia sanctions, to hold the Administration accountable for its actions in this area, and to ensure that the strongest possible sanctions against Russia are implemented and remain in place.
Bipartisanship
I would like to take a few minutes to address how I will approach working with my colleagues on the other side of the aisle as Chairwoman. Throughout my career, I have looked for opportunities to build consensus and work across the aisle on commonsense solutions to benefit hardworking Americans.
As Chairwoman I will continue to find areas where we can all work together. Ranking Member McHenry and I have a relationship, and just last Congress we worked together on several bills: the Fix Crowdfunding Act, to boost crowdfunding and enhance investor protections, and the Supporting America’s Innovators Act, to make it easier for more angel investors to finance startup companies and small businesses. The Supporting America’s Innovators Act became law.
Previously, we also worked together on the Promoting Transparent Standards for Corporate Insiders Act, a bill to limit the ability of corporate insiders to illegally trade on non-public information. I am very pleased to announce that Ranking Member McHenry and I are reintroducing the Promoting Transparent Standards for Corporate Insiders Act together.
So I am very hopeful that we will be able to get some good bipartisan work done in Committee. Some of the big issues we are going to try to work on a bipartisan basis include long-term reauthorization and reform of the National Flood Insurance Program (NFIP), Terrorism Risk Insurance (TRIA), and the reauthorization of the job-creating Export-Import Bank.
And so, it is a new day in Congress and for the Financial Services Committee.
As Chairwoman, I will continue to work every day to create opportunities for hardworking Americans, ensure fairness, and protect the economic wellbeing of all Americans. I will also continue to hold this Administration and its appointees accountable.
Thank you again to the Center for American Progress for having me today!






Black Press
Four Tips to Help You Plan a Holiday “Staycation”
“A great staycation starts when you treat your hometown like a destination – book one ‘anchor’ experience, stay somewhere that changes your scenery, and leave room for a little spontaneity,” said Steve Orens, President of FROSCH by Chase Travel, a leading travel agency. “My favorite staycation tip is to make it easy on yourself: choose a walkable area, plan one highlight each day, and let the hotel do the heavy lifting – warm beds, quick breaks, and fewer logistics.”

Holiday travel can be exciting, but between costs, crowded airports and packed schedules, sometimes the idea of staying home can be much more appealing.
If you still want to get away without the hassle of an actual getaway, consider a holiday staycation.
By remaining close to home, you can experience your city from a fresh perspective without the stress of a long trip. Whether you book a night at a local hotel, check out a new neighborhood or just finally get around to seeing that landmark attraction that’s been on your to-do list, you can make staying at home feel like a real getaway.
Here are four tips you can use to create an amazing holiday at home this season:
1. Treat your hometown like a destination
One common theme surrounding area attractions is that they’re more likely to be packed with tourists than locals. If that popular museum, tour or other institution is always “there,” it can be easy to avoid it and say you’ll get there eventually.
A staycation provides a great opportunity to approach those kinds of places like a tourist. Start by making a short list of places or experiences you’ve always wanted to try but never seem to prioritize. You might include a museum, holiday market, historic site, restaurant or neighborhood, or you might attend a holiday-related performance that’s an annual late fall or winter tradition in your area.
“A great staycation starts when you treat your hometown like a destination – book one ‘anchor’ experience, stay somewhere that changes your scenery, and leave room for a little spontaneity,” said Steve Orens, President of FROSCH by Chase Travel, a leading travel agency. “My favorite staycation tip is to make it easy on yourself: choose a walkable area, plan one highlight each day, and let the hotel do the heavy lifting – warm beds, quick breaks, and fewer logistics.”
2. Spend the night away
A hotel stay can provide a change of scenery that makes you feel like you’re enjoying a getaway.
Consider a traditional hotel, bed and breakfast or rental property where you can walk to restaurants, shopping, entertainment or holiday activities. An upscale hotel can also be the centerpiece of your staycation, allowing you to enjoy fine dining, a fitness center, spa services or other on-site experiences.
If you want a quieter, more relaxed experience, find a hotel “off the beaten path,” but still close to home, to enjoy the rhythms and sounds of nature.
3. Be flexible
If your schedule allows, plan your staycation for a weekday or less crowded period — like the days between Christmas and New Year’s Eve — rather than a peak weekend. Hotel rates in the middle of the week tend to be cheaper, and it might be easier to grab a restaurant reservation or performance tickets. Locations might be less crowded as well during the week, making it easier to get around.
Book some experiences in advance to save money but stay open to spontaneous opportunities once you arrive. You might find some great last-minute deals.
4. Try something new
Even if you think you’ve seen everything your hometown has to offer, there’s always something new to explore or discover.
Check out a neighborhood you usually drive through and visit the local shops and other businesses. You can also try a new cuisine at a neighborhood restaurant or kitchen.
Sometimes what’s old can be new again during the holiday season, so if you want to go back to your favorite restaurants and other popular spots, do so with fresh eyes. Order from the eatery’s holiday menu or take a walk when lights, decorations and seasonal programming transform many communities.
Other helpful tips
Although staying at home can eliminate major travel costs, expenses can still add up quickly. Make a staycation budget and then consider ways to help keep costs down.
“A ‘smart’ staycation is one you can pay for comfortably: choose dates with better rates, book flexible options, and keep a small buffer for surprises,” added Orens. “The goal of a staycation is a real reset. Even if you’re close to home, give yourself permission to unplug and find moments to treat yourself – say yes to room service, a spa hour, or a new restaurant you’ve been saving for ‘someday.’”
If you have rewards points from credit cards or loyalty programs, put them toward your hotel to get a free or cheaper night’s stay. Local museums, cultural institutions and attractions often have resident discounts, reduced-price admission days or seasonal offers. Community calendars can provide information about free or low-cost events like holiday concerts, light displays, markets, park activities and other events. If a performance doesn’t normally sell out, wait until the day before or day of to buy tickets, as prices are often reduced and you can find great seats.
With a little creativity, you might find everything you’d want in a holiday vacation. You can enjoy good food, new experiences and an escape from your daily routine – all right at home.
For more financial health tips, visit https://www.chase.com/travel/guide.
For informational/educational purposes only: Views and strategies described in this article or provided via links may not be appropriate for everyone and are not intended as specific advice/recommendation for any business. Information has been obtained from sources believed to be reliable, but JPMorgan Chase & Co. or its affiliates and/or subsidiaries do not warrant its completeness or accuracy. The material is not intended to provide legal, tax, or financial advice or to indicate the availability or suitability of any JPMorgan Chase Bank, N.A. product or service. You should carefully consider your needs and objectives before making any decisions and consult the appropriate professional(s). Outlooks and past performance are not guarantees of future results. JPMorgan Chase & Co. and its affiliates are not responsible for, and do not provide or endorse third party products, services, or other content.
Deposit products provided by JPMorgan Chase Bank, N.A. Member FDIC. Equal Opportunity Lender.
© 2026 JPMorgan Chase & Co.
Black Press
Veterans Housing Project Proposed for South Richmond
According to the development team’s presentation, the project has an estimated total cost of nearly $158 million. The presentation outlines five phases encompassing entitlement and construction documents, community outreach, soil remediation and utility work, podium and building construction, solar technology integration, and interior buildouts.
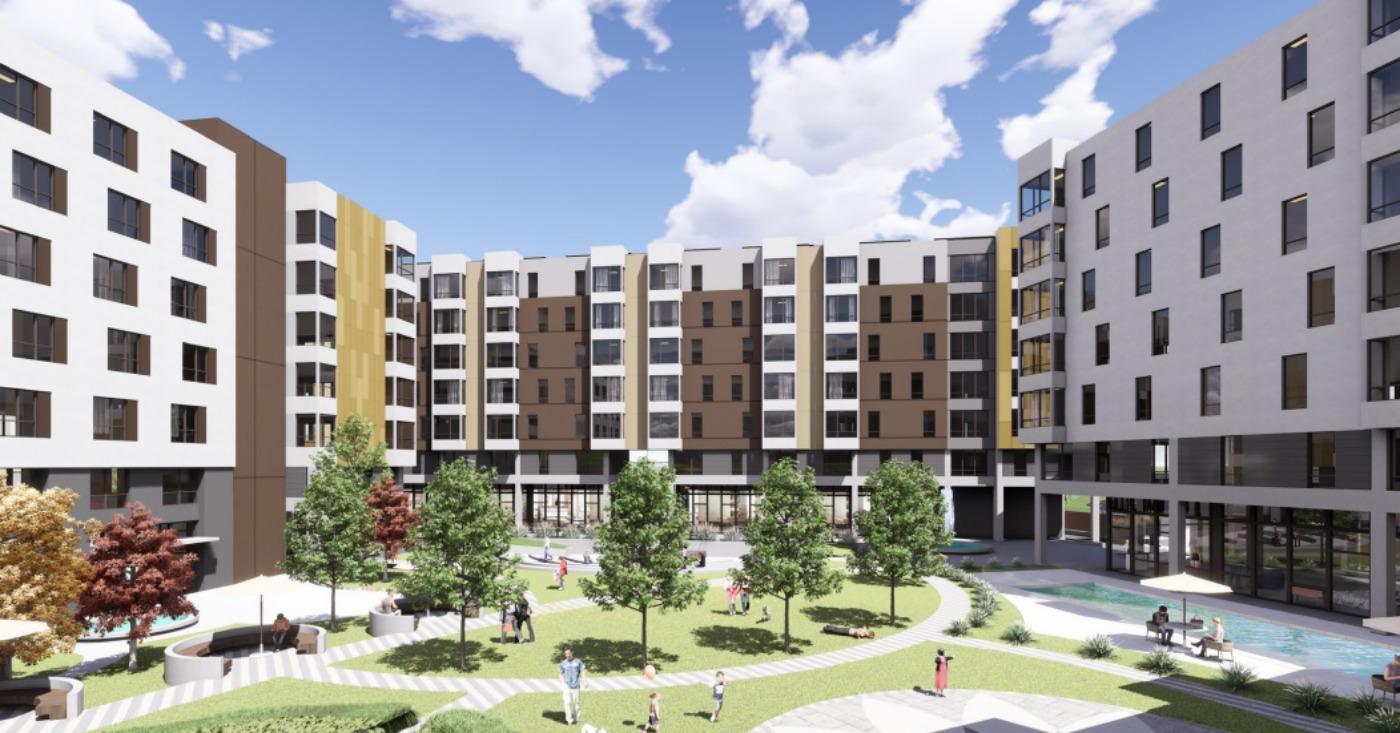
A proposed mixed-use development at 338 Carlson Blvd. could bring hundreds of homes and support services for military veterans to South Richmond.
Led by the Richmond-based Veterans Resource Program in partnership with Eagle Environmental Construction & Development, the proposal covers an approximately 2.3-acre property the nonprofit acquired in 2018.
The proposal features a multi-building residential development with various apartment sizes, though city documents and developer materials cite conflicting totals ranging from 226 to 268 units.
The proposal also includes approximately 40,000 square feet of commercial and retail space, about 200 parking spaces, and an entrepreneurial training and job-development component intended to connect veterans with economic and workforce opportunities.
According to the development team’s presentation, the project has an estimated total cost of nearly $158 million. The presentation outlines five phases encompassing entitlement and construction documents, community outreach, soil remediation and utility work, podium and building construction, solar technology integration, and interior buildouts.
Founded in 2011, the Veterans Resource Program provides housing assistance and other services to veterans, including those experiencing homelessness or transitioning from incarceration.
The proposal aims to advance Richmond’s affordable housing goals while connecting veterans with housing and supportive services. Details of affordability and veteran eligibility remain to be clarified.
The Richmond City Council was scheduled to receive an informational presentation on the project at its Oct. 6 meeting, following a continuance from Sept. 22. The item does not seek project approval or city funding. Any future request for city financial assistance or other public resources would require separate consideration and approval.
Black Press
Marin County Supes Expand Small Business Options with Home Kitchen Pilot Program
“This will deliver immediate financial relief to entrepreneurs in areas like Marin City, West Marin and the Canal neighborhood, removing barriers right where economic opportunity is needed the most,” said Shannon Bell, consumer protection supervisor with Marin County Environmental Health Services, at the meeting.
The Marin County Board of Supervisors adopted a three-year pilot program that will allow cooks and food entrepreneurs to prepare and sell meals from their homes on Sept. 29
The Microenterprise Home Kitchen Operation program, or MEHKO, will establish a permitting process for small-scale home food businesses. California state law allows licenses if local governments opt in.
“This will deliver immediate financial relief to entrepreneurs in areas like Marin City, West Marin and the Canal neighborhood, removing barriers right where economic opportunity is needed the most,” said Shannon Bell, consumer protection supervisor with Marin County Environmental Health Services, at the meeting.
MEHKO licenses fill the gap between cottage food permits, which only apply to non-potentially hazardous foods like baked goods and jams, and full commercial kitchens.
Microenterprises can serve as commissaries for up to two mobile food operations; they require food to be prepared and served the same day. They are exempt from commercial facility requirements, such as industrial grease traps and commercial stove hoods.
The program allows takeout or on-site dining with strict limits of 30 meals per day, or 90 meals per week, and an annual sales cap of $100,000.
The pilot would begin March 1, 2027, and permits would be capped at 100 per year. Application fees are $725 with an annual renewal fee of $414, but fee waivers for a third of the permits are reserved for low-income communities.
After two years, supervisors will consider making the program permanent.
“By eliminating the need for commercial leases and expensive equipment, entrepreneurs can safely test their businesses and ideas with minimal financial risk,” Bell said. According to statewide data from the Cook Alliance, 85% of MEHKO operators are women, immigrants, and people of color, and over 70% rely on this income to support their families, she said.
Bell also said unpermitted sales are already happening in areas like the Canal.
Local Vendors Seek a Legal Path
Marina Palma advocates for San Rafael’s Canal neighborhood, which is home to a vulnerable community of over 13,000 low-income residents. About 84% are Latino and roughly half of all households spend more than 50% of their income on housing.
Palma told the board that the pandemic caused many Canal residents to lose their jobs, and that’s why the neighborhood has so many vendors selling food in public. Because they have no license, enforcement actions can be harsh.
“They have really high tickets of $600, and their food has been thrown away,” said Palma.
She said MEHKO would help vendors get an official license, but she questions whether vendors will need a Social Security number and be legally in the country.
According to the home-chef’s national nonprofit Cook Alliance, MEHKO applicants need no proof of citizenship nor a Social Security number to obtain a permit.
“I’m from Mexico, and I’m one of the mobile vendors,” said Elsie Vega through a Spanish translator. “I have two jobs. Everything is pricey — house, food, everything. I am here to work hard, to pay taxes. I don’t make enough money to pay the community kitchens.”
MEHKO license holders must pass inspection under the oversight of the Marin County Department of Environmental Health Services and comply with local zoning, parking and noise ordinances.
California authorized MEHKO programs in 2019. Seventeen counties have since adopted them, including Sonoma, San Mateo, Solano, Contra Costa, Alameda and Santa Clara counties.
Other commenters who spoke in favor of the program represented a range of food system and small business organizations. They included the Agricultural Institute of Marin, which operates nine Bay Area farmers markets, the University of California Cooperative Extension, the Cook Alliance, the West Marin Food Systems Group, which coordinates farm-to-school food access, and the Marin Small Business Development Center.
Black Press
AC Transit Labor Unions Back Director Joel Young
ATU Local 192 Vice President Nathaniel Arnold stated “our support reflects confidence in Young’s leadership and experience as the longest-serving member of AC Transit’s current Board of Directors. His experience is particularly important as AC Transit confronts serious fiscal challenges while working to preserve and strengthen service.
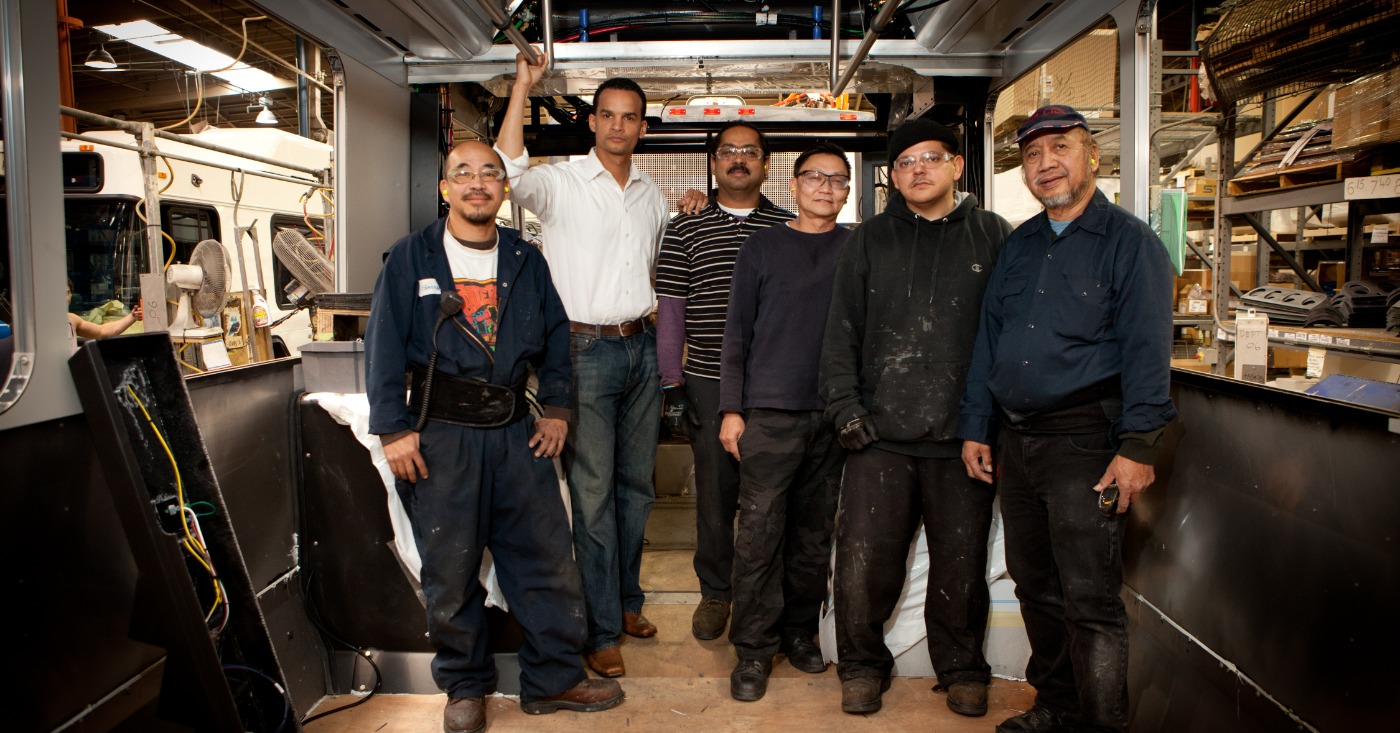
In the AC Transit Ward 3 election, AC Transit’s labor organizations have recently expressed their endorsement for Director Joel Young, recognizing his longstanding commitment to public transportation, workforce investment, and the employees who keep AC Transit moving every day.
Those unions include the Amalgamated Transit Union Local 192, the International Brotherhood of Electrical Workers Local 1245, and the American Federation of State, County and Municipal Employees Local 3916.
ATU Local 192 Vice President Nathaniel Arnold stated “our support reflects confidence in Young’s leadership and experience as the longest-serving member of AC Transit’s current Board of Directors. His experience is particularly important as AC Transit confronts serious fiscal challenges while working to preserve and strengthen service.
“At a time when difficult decisions lie ahead, Young brings institutional knowledge, longstanding relationships, and a demonstrated commitment to public transportation.
“Since joining the board in 2009, Young has served in key leadership roles, including president and vice president, helping guide AC Transit through periods of growth, innovation, and change.
During his tenure, he helped AC Transit secure more than $600 million in funding to support critical transportation investments. Young has also helped advance workforce development initiatives, support transit technology improvements, expand AC Transit’s zero-emission bus fleet, and strengthen the District’s national presence on transportation policy issues.
His leadership has extended beyond the Bay Area.
Young has represented AC Transit on the national stage, including participation in the White House Roundtable on Clean Bus Manufacturing, where transit leaders and policymakers discussed the future of clean transportation and domestic manufacturing.
Black Press
Locals Can Get Locally Grown Produce Delivered Through Urban Tilth
The standard price is $50 per week, which Urban Tilth says reflects the true cost of fresh, sustainably sourced, locally grown produce. Urban Tilth offers a subsidized “Food for All” price of $15 per week for individuals and families with extremely limited financial resources. Both options provide the same produce and service.
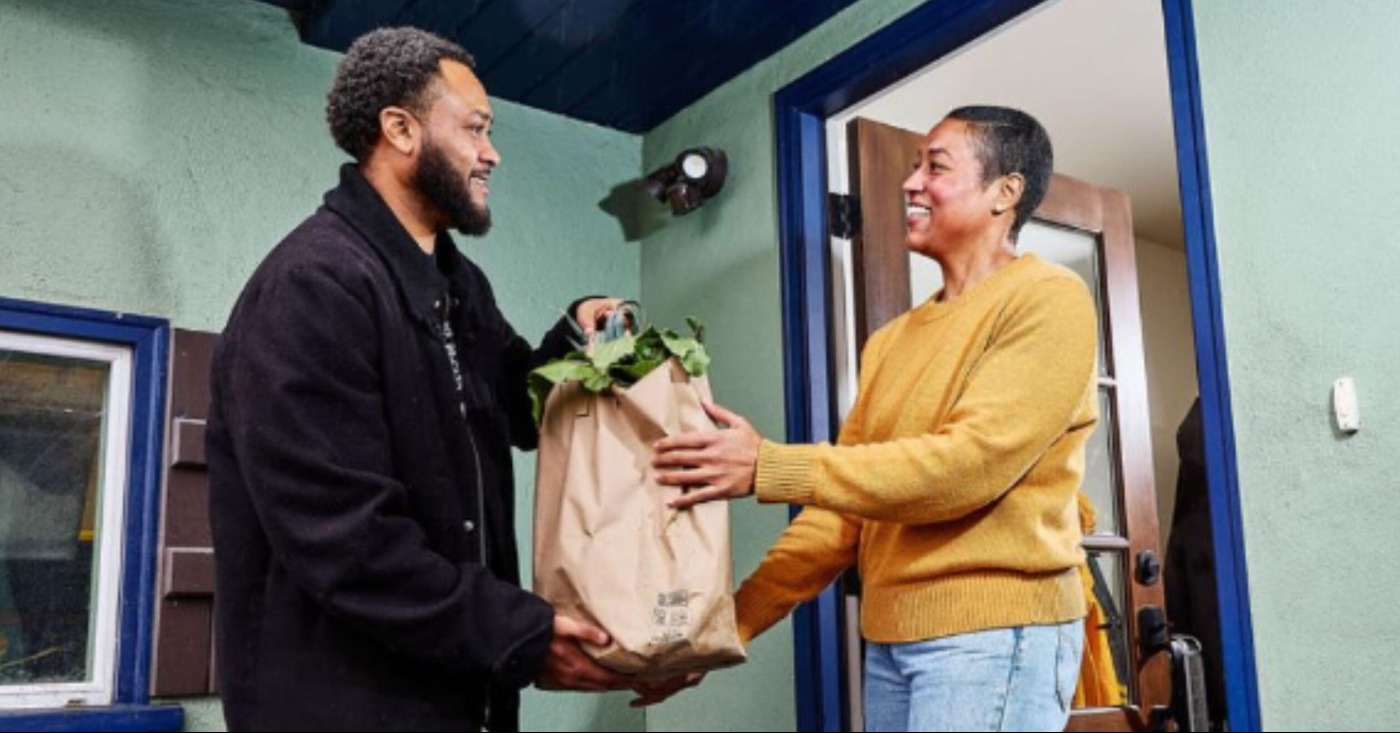
West County residents can receive locally grown produce through Urban Tilth’s Farm to Table Community Supported Agriculture (CSA) program, with home delivery and pickup options available.
Contra Costa County Supervisor John Gioia highlighted the program in his newsletter, pointing out that his district office in El Cerrito serves as a pickup location.
Weekly or bi-weekly subscriptions include seasonal greens, vegetables, fruits and herbs. Produce comes from Urban Tilth’s North Richmond Farm and farms within 200 miles of Richmond, including small family farms and those owned by BIPOC, women and LGBTQIA+ growers.
Subscriptions also support hands-on job training for local youth and volunteer opportunities.
The standard price is $50 per week, which Urban Tilth says reflects the true cost of fresh, sustainably sourced, locally grown produce. A subsidized “Food for All” price of $15 per week is available for individuals and families with extremely limited financial resources. Both options provide the same produce and service.
Gioia’s office is located at 11780 San Pablo Ave., Suite D, in El Cerrito. To sign up or learn more about pickup and delivery options, visit urbantilth.org/heal/csa.
Black Press
Should You Have to Pay to Hear the Gospel?
ST. LOUIS AMERICAN — Pastor Philip Anthony Mitchell of Atlanta’s 2819 CHURCH and Tim Timberlake of Celebration Church in Jacksonville, Florida, are at the center of a social media debate. The controversy stems from ticket prices for their “Street Preachers” podcast tour, with general admission tickets reportedly costing around $60 and VIP options up to $200.
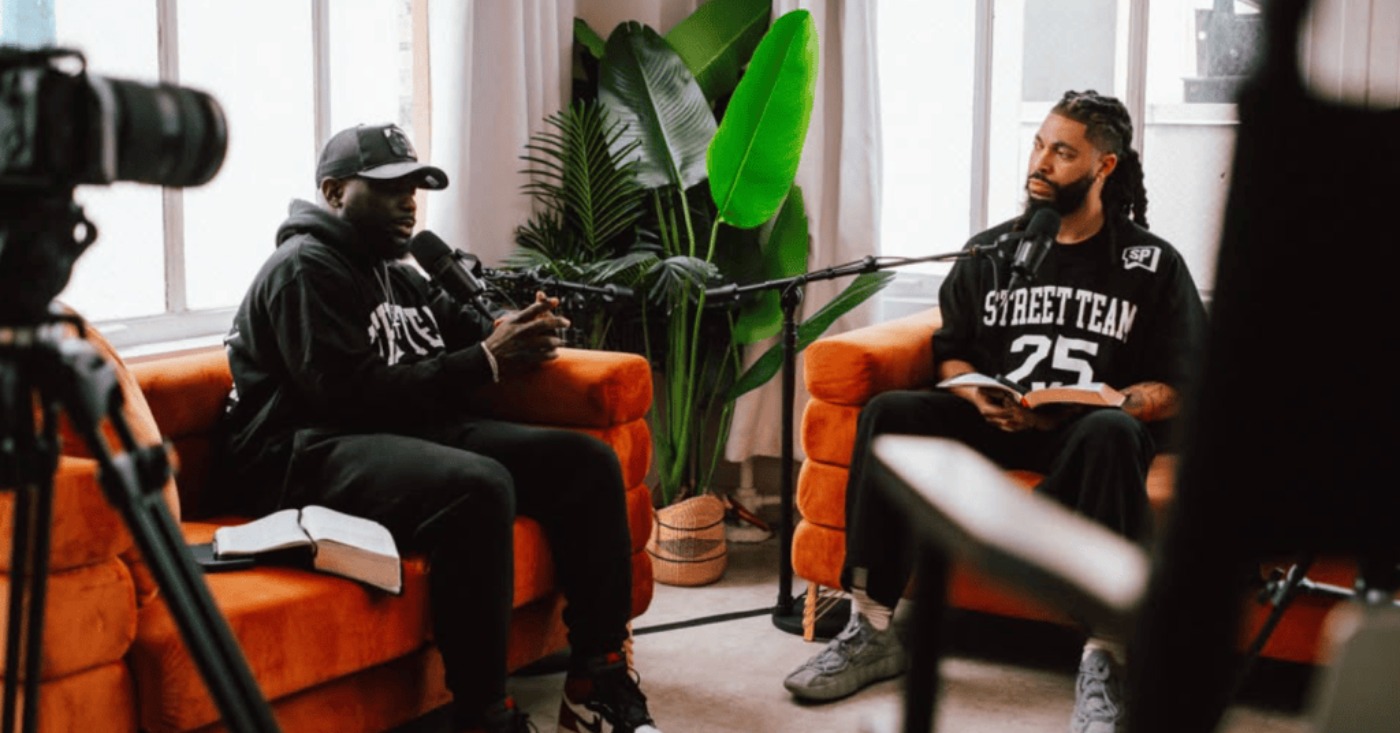
For generations, the Black church has passed the offering plate to keep the lights on, pay the preacher, help the poor and carry the Gospel beyond its walls. But what happens when the preacher leaves the sanctuary, takes a popular Christian podcast on tour — and charges admission?
That question has placed Pastor Philip Anthony Mitchell, founder and lead pastor of Atlanta’s fast-growing 2819 CHURCH, at the center of a heated social media debate.
Mitchell and Tim Timberlake, senior pastor of Celebration Church in Jacksonville, Florida, host “Street Preachers,” which its official website describes as a “raw, unfiltered podcast” committed to spreading the Gospel.
‘A brood of vipers’
The controversy began after ticket prices for the podcast’s 2026 tour circulated online. General admission tickets reportedly cost about $60 before fees, with premium options, including a VIP meet-and-greet package, priced at $200. Critics questioned whether ministers should charge people to hear the Gospel.
Others defended the pastors, arguing that Christian events require venues, transportation, security, equipment and staff.
Mitchell answered critics from the pulpit last month, calling them “a brood of vipers.” He said the podcast is a separate, personal project and that neither his church nor Timberlake’s is bankrolling it.
“Now we have decided to go on a tour to take the gospel to cities, and because that’s not funded by 2819, and it’s not funded by Celebration Church, Tim and I gotta do that with our own pockets,” Mitchell said. “It’s why there is tickets. We have to pay for venues and security and productions and staff from our own pockets.”
Mitchell called some critics “ignorant” and said they did not know that a child was healed through faith during one of the events.
“And you want to complain about a 60 ticket?” he said. “So hate on!”
Worship service vs. media event
Mitchell maintains that “Street Preachers” is an independently produced podcast tour, not a worship service, and that ticket revenue helps cover production costs.
Yet the presence of pastors, Scripture and Gospel language makes the distinction less clear to some believers.
The official tour website lists all eight 2026 stops as sold out. Promotional material announcing additional dates promised, “Better ticket options. Same Gospel. Same move of God.”
Corporate prayer gathering
The language gets to the heart of the dispute. Some Christians argue that no one should be kept outside because they cannot afford a ticket. Others say the Gospel remains free even when people pay for the venue and experience surrounding its presentation.
The paid podcast tour, however, is not Mitchell’s only large-scale gathering. On Oct. 10, 2819 CHURCH will host “ACCESS — That Powerful Hour of Prayer” at AT&T Stadium in Arlington, Texas. Admission is free.
2819 CHURCH has said 80,000 free tickets were claimed before registration reopened.
The contrast raises another question: What makes one Gospel-centered event a ministry supported by donors and another a production supported by customers?
Unfiltered preaching, youth appeal
Mitchell’s congregation, composed largely of young Black adults, grew from fewer than 200 weekly worshippers in 2023 to about 6,000, according to the church. Some worshippers arrive before sunrise to secure a place inside.
His appeal rests partly in an intense, vulnerable and raw preaching style.
“I’m preaching without watering that down, without filtering out things that we think might be too controversial,” Mitchell told The Associated Press.
That visibility has also brought scrutiny of his theology, associations, travel, security and the businesses surrounding his ministry.
But the controversy reaches beyond Mitchell and Timberlake. Christian music concerts charge admission. Seminaries charge tuition. Religious publishers sell Bibles, books and devotionals. Churches pay musicians, media teams and guest preachers. Money becomes particularly uncomfortable, however, when an event is presented simultaneously as ministry and entertainment.
Ministry vs. entertainment
Supporters should not assume every dollar collected becomes personal profit. Critics, however, question whether lower-cost seats, sponsored tickets or free admission for people who cannot pay should be part of a Gospel-centered event.
The Black church always has required resources for ministry. It also has carried a sacred responsibility to make room for people with little or nothing to give.
The sold-out “Street Preachers” tour shows people are willing to pay to attend. The free ACCESS gathering offers a different model. The challenge is preserving that open door as Christian ministry increasingly adopts the machinery — and economics — of popular entertainment.
The post Should you have to pay to hear the Gospel? appeared first on St. Louis American.
Based on reporting by St. Louis American.

Black History: Gladys West Mathematics Helped Make GPS Possible

Richmond’s Secret Bank: The True Reformers Story #shorts

7 USB-C Ports + Wireless Charging: Power Up Your Family #shorts

Urban League, AT&T Expand Digital Skills and Laptop Access in St. Louis

Attend a Green Line Bus Rapid Transit Open House

VIN Check: Avoid Truck Recalls Before Buying! #shorts

Defender Parking Camera & Screen Features Explained #shorts

Find Black-Owned Banks & Credit Unions Easily #shorts

HBCU Homecoming: A never-miss annual tradition

News Observer Weekly — October 14, 2026 | Top 5 Stories of the Week

The Youngest American Killed in the Vietnam War

Passing for White, Fighting for Black America: The Courage of Walter White

OP-ED: Haiti TPS: Have We Lost Sense of Humanity?

OP-ED: How Does Your State Rank for Pre-K?

NFL: Week Two Recap | Jalen Hurts did not fold; Caleb Williams exits game with injury

Remembering Chauncey Bailey as Student Journalists Face Threats to Truth-Telling

Headlines and Hot Topics 📱

NEWSOM, KAMALA & 2028: THE POLITICAL CALCULUS BEGINS 📱

Peter Magubane: a Camera Against Apartheid

Obama Urges Democrats to make AI a Priority 📱
Black History: Gladys West Mathematics Helped Make GPS Possible
Richmond’s Secret Bank: The True Reformers Story #shorts
7 USB-C Ports + Wireless Charging: Power Up Your Family #shorts
Urban League, AT&T Expand Digital Skills and Laptop Access in St. Louis
Attend a Green Line Bus Rapid Transit Open House
VIN Check: Avoid Truck Recalls Before Buying! #shorts
Defender Parking Camera & Screen Features Explained #shorts
Find Black-Owned Banks & Credit Unions Easily #shorts
HBCU Homecoming: A never-miss annual tradition
News Observer Weekly — October 14, 2026 | Top 5 Stories of the Week
-
 Black Press1 week ago
A $2.1 Trillion Wellness Industry Never Built a Daily Practice for Black Children. So This Atlanta Family Did.
-
 BlackPressUSA7 days ago
Latinas Deserve Equal Pay. Unions Help Make It Happen.
-
 Art1 week ago
Montclair Brewery: Brewing Culture, Community, History
-
 Black Press3 days ago
All Skinfolk Ain’t Kinfolk
-
 Black Press1 week ago
COMMENTARY: But God!
-
 Black Press1 week ago
Safety Concerns at Southern University
