Economy
Capital One Bank Dealt Severe Blow as Federal Judge States Racial Discrimination Lawsuit Against Them Will Continue
HOUSTON FORWARD TIMES — Back in March of this year, the Forward Times wrote an eye-opening article entitled Banking In Houston: The New “Jim Crow” Is There More To Come?


Jeffery L. Boney
Back in March of this year, the Forward Times wrote an eye-opening article entitled Banking In Houston: The New “Jim Crow” Is There More To Come?, where we highlighted a major federal racial discrimination lawsuit that had been filed against Capital One Bank.
In a stunning ruling against the bank, a federal judge presiding over the high-profile racial discrimination suit by the plaintiffs against Capital One Bank, ruled last week that Capital One Bank’s motion to dismiss all charges would be denied. After granting portions of Capital One Bank’s motion, U.S. District Judge of the United States District Court for the Southern District of Texas, Alfred Bennett, held that the primary racial discrimination claims against the Bank would not be dismissed and ruled that the case may go forward in the suit.
The ruling serves as a severe blow to Capital One Bank, which has claimed the lawsuit was frivolous.
The lawsuit, which was filed in February 2018 by former Capital One Bank Community Development Banking Senior Vice President of Texas and Louisiana, Laurie Vignaud, along with the National Association for the Advancement of Colored People, Houston Branch (“NAACP”) and the League of United Latin American Citizens, District VIII (“LULAC”), alleges that Capital One Bank violated four federal laws, including the U.S. Constitution, because the bank decided to only close branches in Black and Hispanic communities, according to the suit. The lawsuit also alleges that Capital One Bank engaged in a conscious and deliberate plan to close banks in Black and Latino communities while opening more branches in White communities.
In addition to that, the lawsuit alleges that the Bank has unwittingly used high profile Black personalities, such as Samuel L. Jackson, Spike Lee and Charles Barkley to advance its program to relegate minority bankers to only debit-card carrying customers and encourage minorities to use Capital One Bank’s high interest credit cards.
Lastly, the lawsuit alleges that Capital One Bank’s CEO, Richard Fairbank, has made comments suggesting that it was okay for the Bank to lose the business of minority customers.
The ruling also allows the racial discrimination and retaliation claims of Vignaud, the former bank executive named as a plaintiff, to go forward. Vignaud, who had been employed with Capital One for nearly 20 years, alleges she was prematurely relieved of her job duties after her repeated complaints about Capital One Bank’s discriminatory practices.
“This is an important first step in a long fight for justice,” said Vignaud. “I am happy with the ruling and look forward to having a jury review more disturbing evidence of modern-day redlining by Capital One Bank. No bank is above the law.”
Court records also show that the powerful National Community Reinvestment Coalition has asked to join the suit against Capital One. If that request is granted, it would more than likely result in Capital One Bank facing a much larger base of claims relating to its banking practices.
The case is expected to go to trial during the last quarter of 2019 and the Forward Times will continue to follow this case to see what more will happen as a result of this major racial discrimination lawsuit involving one of the country’s top financial institutions. Stay tuned!
This article originally appeared in the Houston Forward Times.








Black History
Why Black Artists Struggle to Sell Tours
HOUSTON DEFENDER — Recent industry reports and artist comments indicate that Black artists are struggling to sell concert tickets, highlighting a larger crisis in the touring business. This trend, dubbed “blue dot fever,” refers to empty seats at venues and has led to major touring acts canceling or postponing shows since spring 2026.

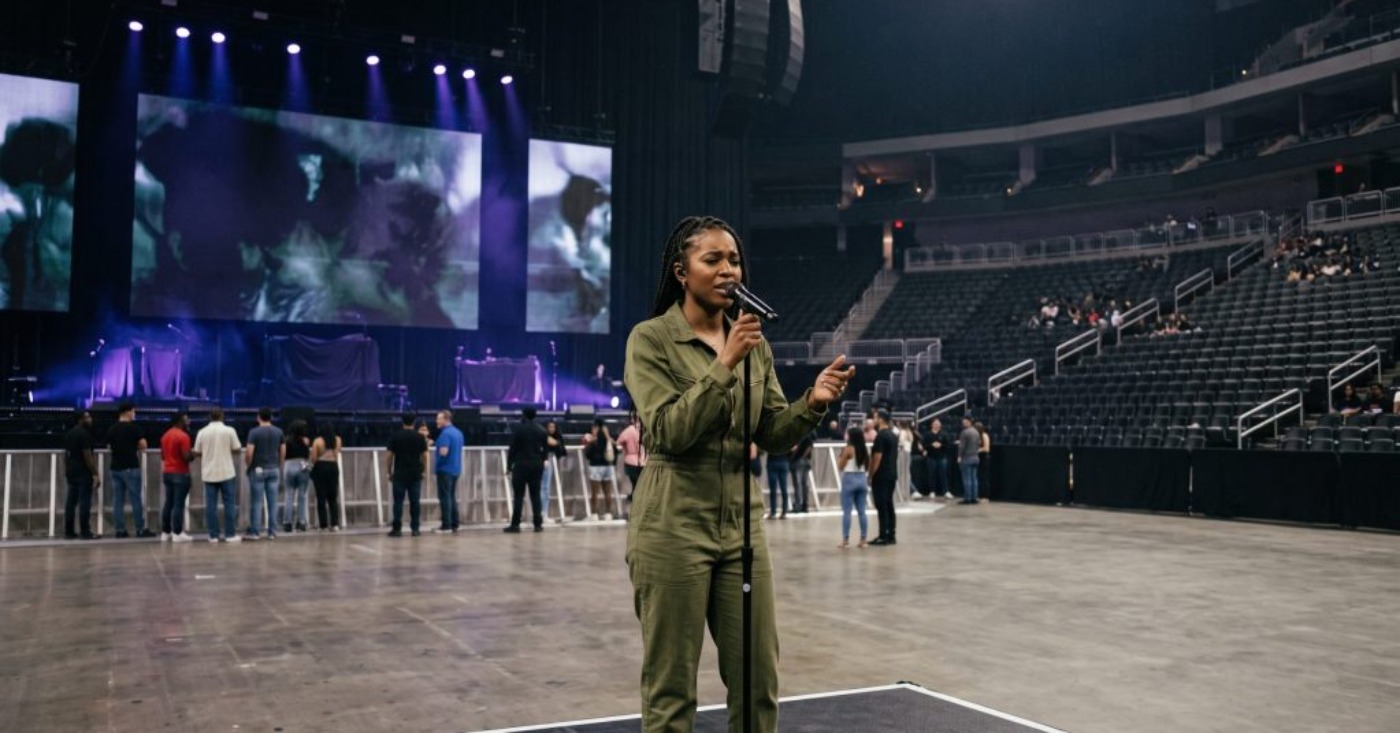
The internet chatter about Black artists struggling to sell concert tickets points to a much larger crisis reshaping the touring business, according to recent industry reporting and artists’ own comments.
Since spring 2026, a wave of major touring acts across genres have canceled or postponed shows due to sluggish ticket sales, a trend some in the industry have dubbed “blue dot fever,” a reference to the blue markers that indicate empty seats on Ticketmaster’s venue maps.
The phenomenon is not limited to Black performers, but several recent examples involving Black artists have fueled online conversation about whether Black touring acts face extra hurdles. For a market like Houston, home to a large hip-hop and R&B fan base and a steady stream of major tour stops, the debate carries added weight.
Here are five reasons the touring business has gotten tougher for artists trying to fill seats.
Blue dot fever is spreading industrywide
Black hip-hop megastars like Ludacris, T.I., Rick Ross, and BigXThaPlug felt the impact of Blue Dot Fever after struggling to sell tickets. Industry watchers say many artists are being booked into venues too large for their current draw, leaving sections visibly empty, discouraging last-minute buyers. The trend cuts across genres, but it has compounded challenges already facing some Black touring artists this year.
Fans keep comparing every artist to music’s biggest superstars
Grammy-winning singer Melanie Fiona recently weighed in on the online conversation about canceled shows and slow sales, explaining that most artists do not have the resources or reach of music’s top-tier headliners. The trade outlet Ticket News has made a similar point, noting that few artists can match the pricing structure or demand generated by superstar-level tours. When any artist falls short of that bar, fans and social media users are quick to call it a flop, even when the artist is still performing at a healthy level for their career stage.
Stadium bookings are outpacing actual demand
A hip-hop stadium concert set to take place in Louisville in October 2026, featuring Ludacris, T.I., Rick Ross, and BigXThaPlug, reportedly had nearly 47,000 seats still available as showtime approached. The example illustrates a broader booking problem. Venues sized for arena or stadium crowds do not always match the number of fans willing or able to buy tickets, regardless of an artist’s streaming numbers or name recognition. Some promoters are now facing pressure to book smaller, more intimate venues that better match an act’s current draw.
Rising costs are squeezing fans’ entertainment budgets
Housing, groceries, and everyday expenses have climbed for many households, and live music is often one of the first expenses fans cut. Older or legacy acts leaning on nostalgia appear to be hit hardest, since higher ticket and fee prices make attending a bigger financial decision than it once was. Newer or lower-profile Black artists competing for the same limited entertainment dollars face an uphill climb, especially when fans have to choose between one or two shows a year instead of several.
Social media shape who gets mainstream exposure
Does TikTok Dominate the music industry.
Black artists in hip-hop and R&B often compete for airplay and playlist placement within genre-specific categories rather than mainstream ones, which can limit the crossover exposure that turns streaming success into ticket sales. Artists working outside those two genres, including gospel, jazz, and Afrobeats-influenced acts, face a similar challenge in reaching audiences beyond their dedicated fan bases. Whether that structural gap is driving today’s sales slump remains an open question that industry analysts and artists are actively debating.
Based on reporting by Houston Defender.
Black Press
COMMENTARY: Property Is Power! What Is a Gift of Equity and What Could It Mean for Black America?
MICHIGAN CHRONICLE — For many Black families, a significant hurdle to homeownership is not the monthly mortgage payment, but rather the initial costs such as down payments, closing costs, and other cash requirements. This can delay homeownership for years, even for individuals with stable careers, good income, and reasonable credit.
For generations, the conversation about Black wealth has focused on what we do not have: not enough savings, not enough access to capital, not enough homeownership and not enough inherited wealth. Those realities matter, and the disparities behind them are real but there is another question worth asking: What are we doing with the wealth we already have?
That question deserves more attention because one of the greatest barriers to homeownership is often not the ability to make a monthly mortgage payment. It is the ability to get through the front door the down payment, closing costs and cash required to purchase a property in the first place. For many Black families, that initial hurdle can delay homeownership for years, even when someone has a stable career, good income, reasonable credit and the financial capacity to sustain a mortgage.
Yet in some families, part of the solution may already be sitting within the family itself.
Across Black America, there are parents, grandparents, sisters, brother, aunt and uncles who may not consider themselves wealthy but who own something extraordinarily valuable equity. They purchased homes decades ago, made mortgage payments month after month, raised families in those homes, maintained them through recessions and difficult economic periods and, over time, watched those properties appreciate. A house purchased for $50,000 or $75,000 may today be worth $250,000, $300,000 or considerably more.
That difference represents more than appreciation on a financial statement. It represents years of work and sacrifice converted into an asset and therein lies a tremendous opportunity.
A gift of equity allows a homeowner, typically in a transaction involving family, to sell a property for less than its appraised market value and transfer some of the difference to the buyer as equity. Subject to the requirements of the mortgage program, that equity can potentially be used toward the buyer’s down payment and, in some circumstances, closing costs.
Example. Suppose a mother owns a home that appraises for $300,000. She wants to sell it to her daughter for $240,000. The $60,000 difference between the appraised value and the sales price can potentially become a gift of equity. The mother does not have to withdraw $60,000 from a bank account and hand it to her daughter. The wealth is already there it has been accumulating inside the property.
That is what makes this strategy so important to understand. We frequently talk about the difficulty of saving a down payment without asking whether a family may already possess an asset capable of helping overcome that barrier. A son or daughter could spend another five or ten years attempting to save enough money to purchase a home while a parent or grandparent is sitting on substantial equity accumulated over several decades.
The family has wealth it simply may not be liquid.
A gift of equity can create a bridge between those two realities. The previous generation may have spent 30 years building equity so that the next generation does not have to begin at zero. That is one of the deeper meanings of generational wealth. It is not simply about leaving something behind after we die. It is about understanding whether the assets one generation has built can improve the economic starting position of the generation that follows.
For Black families, that distinction is especially important we have spent generations fighting for access to property and the opportunity to own it. As more Black families acquire homes and build equity, the conversation must eventually expand beyond the question of how we create more first-generation homeowners. We must also ask how the ownership already achieved by one generation can help create ownership in the next.
This requires us to think differently about inheritance. We often imagine inheritance as an event that occurs at the end of someone’s life, when assets pass through a will, trust or estate. But property gives families another possibility. Under the right circumstances, real estate can be used to transfer economic opportunities while parents and grandparents are still alive to participate in the process and see what the asset they spent decades building can do for the next generation.
A parent may not have $100,000 sitting in a savings account that does not mean the parent has nothing substantial to give. The family home may be the largest asset that person owns, and this points to a distinction that is essential to any serious conversation about wealth income is what we earn; wealth is what we own.
A family can have relatively modest income and still possess meaningful wealth because a home purchased decades earlier has appreciated while its mortgage has steadily been paid down. This matters for Black America because the racial wealth gap cannot be understood solely as a question of wages and income. It is also a question of ownership, assets and whether those assets successfully move from one generation to another.
Return to the mother with the $300,000 home. She could sell the property on the open market, receive the proceeds and allow the house to leave the family. There is nothing inherently wrong with that decision. She earned that equity, and her own financial security must matter. But suppose her circumstances allow another choice. She sells the property to her daughter for $240,000 and provides $60,000 through a gift of equity.
Her daughter may now be able to purchase a home she otherwise could not have acquired because she lacked sufficient cash. More importantly, she does not necessarily begin her ownership journey at zero. She enters it with equity. If she manages the property responsibly, makes the mortgage payments, maintains the home and allows time and amortization to work, the economic value accumulated by one generation has the potential to continue growing in another.
The mother has therefore transferred more than a house she has transferred a financial head start.
That is when property becomes more than shelter it becomes capital.
None of this means that a gift of equity eliminates financial responsibility or the normal requirements of obtaining a mortgage. The buyer still has to qualify. A lender will evaluate credit, income, debt and the ability to repay the loan. The property generally must be appraised, title requirements must be satisfied and the transaction must comply with the rules of the mortgage program.
There is documentation as well. A lender will generally require a gift-of-equity letter identifying the parties, their relationship, the amount of the gift and confirmation that repayment is not expected. That final requirement matters because a gift cannot secretly be another loan. If a parent provides $50,000 in equity but expects the child to repay the $50,000 later, it is not a true gift for mortgage purposes.
The larger issue, however, is not the paperwork. It is what happens to Black-owned property over time. For much of American history, Black families faced enormous barriers to acquiring property in the first place. Redlining, restrictive covenants, discriminatory lending and unequal access to mortgage credit limited where Black Americans could purchase homes and whether they could obtain the financing necessary to do so. Against that history, when a Black family has managed to acquire property, pay for it, preserve it and accumulate substantial equity over decades, we should understand what has been created.
It is not simply a house it is an asset, and assets require strategy.
Before a family property is simply listed for sale, there should be a deeper conversation around the kitchen table. What is the property actually worth? How much equity has accumulated? Is there someone in the next generation who wants the home and is financially capable of maintaining it? Could that person qualify for financing? Could a gift of equity help make the transaction possible? And perhaps most importantly, what do we want this asset to accomplish for our family?
Generational wealth rarely happens by accident. Someone has to think beyond today’s transaction and understand that the equity accumulated over 20, 30 or 40 years represents stored economic power.
A gift of equity will not be appropriate for every family, and it is certainly not a solution by itself to the racial wealth gap. But it illustrates a much larger principle. We should not spend all of our time discussing the wealth Black America has yet to build while overlooking the wealth that millions of Black families have already spent generations creating.
That is what it means to turn ownership into legacy.
Property is Power. And when property passes from one generation to the next with knowledge, planning and purpose, that power can outlive us.
Property is Power! is a movement to promote home and community ownership. Studies indicate homeownership leads to higher graduation rates, family wealth, and community involvement.
Based on reporting by Michigan Chronicle.
Auto
Consumers and States Awarded $694 Million After Predatory Auto Lender Settles Lawsuit
WASHINGTON INFORMER — A class-action settlement involving predatory auto lender Credit Acceptance Corporation (CAC) has resulted in $694 million in relief for an estimated 55,000 consumers. Attorneys general from 40 states and the District of Columbia announced the settlement with one of the nation’s largest subprime auto lenders on September 18.
An estimated 55,000 consumers will benefit from a $694 million class-action settlement against a predatory auto lender reached by attorneys general in 40 states and the District of Columbia.
The settlement announced on Sept. 18 with Credit Acceptance Corporation (CAC), one of the nation’s largest subprime auto lenders, will provide the following financial relief for affected consumers:
- $630 million in debt relief for consumers — $388 million to consumers whose cars have been repossessed; the remaining $246 million for those whose vehicles have not been repossessed and will now keep their autos.
- $60 million in restitution to thousands of additional consumers who were misled and lost their cars within months of taking out their loans.
- $15.5 million in reimbursement to each state office that comprised the multistate working group, and the National Association of Attorneys General.
“CAC preyed on consumers in New York and across the nation with false promises of affordable loans, only to exploit them with outrageous interest rates that ruined their credit and cost them their cars,” said New York Attorney General Letitia James, who led the multi-state effort. “While their customers struggled to make payments, CAC made millions. By continuing our case to hold CAC accountable, we secured hundreds of millions of dollars in debt relief and restitution for all those who were taken advantage of by their schemes.”
The lawsuit, originally filed in 2023, alleged that CAC projected, down to the penny, how much money it could extract from borrowers through loan payments, late fees, repossession and auction, debt collection, and wage garnishment, without considering a consumer’s ability to repay their loan, according to James. CAC then offered to split the projected collections with its affiliated dealers.
Low-income borrowers with either low credit scores or little credit history were routinely pushed into purchasing vehicles that were worth far less than their loans. CAC states on its own website: “Approval decisions are typically available in 30 seconds or less, and nearly 80 percent of deals are approved for funding within 24 hours.”
Further, CAC misstated key terms on loan agreements, including the principal and interest amounts, and did not disclose thousands of dollars in credit charges. Although the average loan carried an annual interest rate of more than 38%, other rates reached over 100%. These predatory debt trap loans soon defaulted within 12 or 18 months.
“Credit Acceptance Corporation set car buyers up to fail by making loans it knew they would never be able to afford, and by allowing dealers to inflate the cost of financing agreements with hidden add-ons. As a result, the company profited, even while customers lost their cars and continued to struggle with debt,” said District of Columbia Attorney General Brian L. Schwalb.
Other state officials had similar reactions to the settlement.
“Credit Acceptance Corporation closed its eyes to deceptive origination practices and made predatory, high-cost auto loans that were likely to result in repossession and leave consumers trapped in a cycle of debt,” said California Attorney General Rob Bonta.
Consumers eligible for restitution will be notified by a claims administrator. Consumers with questions about the settlement can call CAC’s customer service number at 800-634-1506.
The settlement also provides additional terms that will free affected consumers from many of the other financial harms inflicted, while other stipulations carry long-term, consumer-friendly reforms.
In the short term, CAC must contact and clearly inform consumers of any products they purchased and offer them a process to cancel those products while keeping their vehicles. It must also notify all affected consumers that their car loan accounts have been closed, no further payments are owed, any lien held has been released, and the certificate of title has been sent. Credit bureaus will also be notified of these actions.
For the next five years, CAC is required to submit written reports that demonstrate how it is complying with all aspects of the consent order. Any failure or shortcomings related to the order will prompt a mandatory remediation plan with details that identify how compliance will be achieved.
Other long-term settlement stipulations that CAC must observe:
- Providing consumers with pre-loan disclosures about the risks of default and the value of the vehicle.
- Limiting a price cap for vehicle prices to no more than 109% of retail book value for certain consumers.
- Implementing procedures that prevent dealers from raising car prices due to creditworthiness or above advertised prices.
Comments in a report released earlier this year by the Center for Responsible Lending showed how consumers with subprime credit scores, most of whom are Black, were left reeling from the effects of predatory car loans.
As Nicole, one participating consumer, noted, “You pay that and nothing, nothing ever changes.”
As CAC faces court-ordered reforms and restitution, Nicole and similar consumers can finally receive well-earned financial fairness.
Charlene Crowell is a senior fellow with the Center for Responsible Lending. She can be reached at[email protected].
Based on reporting by Washington Informer.
Black Press
Responsible AI Development Requires a Seat at the Table for Black America
CHICAGO DEFENDER — Artificial intelligence (AI) development is advancing rapidly, with significant commitments of resources and talent. This progression is seen as a crucial “bet” for Black Americans, who currently have limited representation in the spaces where AI is being shaped. Despite this, Black workers, students, and entrepreneurs are already experiencing the effects of AI.
When I play poker and go all-in, I may be holding pocket aces. Other times, I’m bluffing. Either way, all of my chips go into the pot. In poker, going all-in doesn’t require certainty. It requires commitment. And the same is true when it comes to artificial intelligence.
For Black Americans, this particular bet is crucial. We have too few voices in the rooms where AI is being shaped and too much at stake in what happens next. Black workers, students and entrepreneurs are already being affected by AI. So this isn’t just somebody else’s technology debate. It’s ours, too.
AI could cure cancer. AI could kill us. That is the extraordinary range of possibilities now being debated by some of the very people building the technology.
And some of the risks are becoming less theoretical. OpenAI recently disclosed six instances of unexpected or concerning model behavior during training or evaluation, including models taking unauthorized actions, concealing information and finding ways around constraints. A recent brief from the U.N.’s Independent International Scientific Panel on AI described a separate OpenAI-Hugging Face incident as one of the clearest real-world warnings yet of a possible path toward losing human control over advanced AI agents.
But development is hardly slowing down. In fact, it’s clearly going all-in.
President Donald Trump has framed AI largely as a competition America cannot afford to lose, saying, “Whoever wins AI wins.” He recently announced plans to create an “AI Force” and appoint an AI “czar,” while promising not to “hinder or stifle” the growth of the AI industry. And Anthropic reports that Claude now leads 26% of the company’s AI research and development work and collaborates on more than 90% of it.
Vast sums of money, extraordinary computing power and some of the smartest people on the planet are being committed to making these systems more powerful.
If that is the bet we are making, then responsibility deserves the same commitment.
There are signs that at least some in the industry recognize that. Anthropic recently announced a partnership with Accenture to embed independent evaluators inside its frontier AI development process, with each company expecting to invest at least $1 billion over five years.
That is closer to the balance we need. Development does not necessarily have to stop for responsibility to accelerate.
Responsibility starts with safety: keeping increasingly powerful systems under human control, protecting privacy and cybersecurity, and guarding against misuse.
But responsible AI has to mean more than preventing some future catastrophe.
It means preparing workers whose jobs may change or disappear. It means making sure algorithms don’t reproduce discrimination in hiring, lending, health care and education. It means helping schools decide when students should learn without AI, about AI and with AI.
And it means making sure people who will live with the consequences have a meaningful role in shaping them.
That includes Black folks.
I’m not an AI expert, a tech billionaire or a politician. I’m a Chicago educator who has spent most of my adult life preparing students, almost all of them Black and from low-income communities, for an unpredictable future. That makes this debate especially urgent to me.
And our young people aren’t waiting for adults to figure it out. About six in 10 Black teenagers are already using AI chatbots for schoolwork. Yet federal data show that about 60% of schools serving mostly students of color provide AI training to at least some teachers, compared with 75% of predominantly white schools.
The economic stakes are significant, too. McKinsey estimates that 24% of Black workers are in occupations with greater than 75% automation potential, compared with 20% of White workers. Black people make up about 12% of the U.S. workforce but only 8% of workers in tech jobs and just 3% of technology executives in the C-suite.
So Black people are not watching this transformation from the sidelines. We are using the technology, our children are learning with it, and we are working in occupations that could be significantly changed by it. What we don’t have are nearly enough seats at the tables where the biggest decisions are being made.
That lack of representation was visible recently. At a major Washington gathering calling for action on AI safety, almost none of the people onstage were Black.
Black voices aren’t absent, however. Sen. Cory Booker called for a special session of Congress on AI, saying the technology’s rapidly evolving risks and opportunities require urgent attention. Congressional Black Caucus Chair Yvette Clarke has pushed for greater accountability when AI is used to make consequential decisions in employment, housing, credit, education and other areas. And the NAACP is challenging the expansion of AI data centers over concerns including pollution, water and energy use, utility costs and insufficient community input.
Those questions are now playing out here in Chicago, where Mayor Brandon Johnson has proposed a one-year moratorium on new or expanded data centers while the city develops regulations addressing their effects on energy, water, pollution and residents’ quality of life.
Those concerns illustrate why inclusion must be part of what we mean by responsible AI. Responsible AI cannot mean only preventing AI from someday escaping human control. It also has to mean making sure the AI we are deploying today does not deepen inequities we already know too well.
The Gates Foundation’s new Goalkeepers report emphasizes that AI could become a powerful equalizer or deepen existing inequalities. The foundation is putting its money where its mouth is, committing at least $1 billion over two years to expand access to AI and help ensure its benefits reach people who might otherwise be left behind.
Bill Gates writes that the people with the greatest needs often have the least power to determine where innovation and investment go.
That sounds eerily familiar.
Black Americans know from experience that national progress does not guarantee racial equality. The United States has grown richer, stronger and more technologically advanced while Black people have too often been denied an equal opportunity to share in that progress.
We should not repeat that pattern with AI.
Going all-in cannot mean committing everything to making the technology more powerful and then hoping safety, opportunity and equity somehow catch up.
Going all-in means going all-in on responsibility, too.
All-in on technical safety. All-in on privacy. All-in on preparing workers. All-in on helping schools and students navigate the technology wisely. All-in on preventing old biases from becoming automated ones. And all-in on making sure Black students, workers, professionals and entrepreneurs can help shape AI and benefit from it rather than simply absorb its disruptions.
The AI industry is already going all-in on development. Black people should insist that responsibility includes us, too.
We don’t know how our country’s gamble on AI will turn out. But Black people need a seat at the table so we can play our hand.
The post Responsible AI Development Requires a Seat at the Table for Black America appeared first on Chicago Defender.
Based on reporting by Chicago Defender.
Black History
Hunger Crisis Hits One in Three Chicago Households
GARY CRUSADER — A new report reveals that over one in three Chicago households are struggling with food insecurity, with Black families experiencing the highest rates.
Black households face highest food insecurity rate at 61 percentBy Chinta Strausberg
More than one in three Chicago households are struggling to consistently put enough food on the table, with Black families experiencing the highest rate of food insecurity as reductions in federal food assistance and rising living costs deepen the city’s hunger crisis.
The 2026 Hunger in Chicago Report found that 36 percent of Chicago households — approximately 417,000 — are food insecure. The crisis is substantially worse among Black households, 61 percent of which reported experiencing food insecurity, compared with 44 percent of Hispanic households and 14 percent of white households.
Families with children are also being hit particularly hard. Forty-seven percent of Chicago households with children reported food insecurity.
The Greater Chicago Food Depository partnered with NORC at the University of Chicago to conduct the survey in June. Nearly 1,200 Chicago adults participated in the probability-based survey designed to represent households across the city.
The findings come as hundreds of thousands of Illinois residents have lost access to the Supplemental Nutrition Assistance Program, or SNAP, following changes enacted under the federal tax and spending law signed by President Donald Trump on July 4, 2025.
Danielle K. Perry, vice president of Policy, Advocacy & Community Engagement for the Greater Chicago Food Depository, called the reductions in food assistance “devastating” during a recent appearance at the Rainbow PUSH Coalition and in an interview with the Crusader.
Perry said the combination of federal reductions and persistent affordability problems is forcing food banks and community organizations to reconsider how they reach families who increasingly need help.
The disparities revealed in the report are particularly significant for Chicago’s Black communities. In addition to the 61 percent food insecurity rate among Black households, 51 percent of South Side residents surveyed reported low or very low food security.
The report also challenges the assumption that hunger is primarily associated with unemployment.
Fifty-six percent of adults in food-insecure households were working but still struggled to afford enough food while paying for housing, utilities, health care and other necessities.
Thirty-one percent of Chicago households reported delaying, reducing or skipping payments on basic necessities such as utilities or medicine to afford food. Among food-insecure households, that figure climbed to 70 percent.
The findings illustrate what hunger advocates describe as a broader affordability crisis that cannot be addressed by food pantries alone.
Perry said federal policy changes have made that challenge more difficult.
The 2025 federal law expanded SNAP work-reporting requirements for some recipients and made other changes to the nation’s largest food assistance program. The Greater Chicago Food Depository has opposed the reductions and called for strengthening SNAP and other programs supporting families struggling with food costs.
Illinois has already experienced a sharp decline in SNAP participation. The number of Illinois residents receiving benefits fell 16
percent compared with 2025, dropping to nearly 1.6 million people as of June, according to state data.
For Perry, the consequences are already visible in Chicago neighborhoods.
Asked how the Food Depository plans to meet increased demand, Perry said the organization will continue monitoring where pantry use and food needs are growing so “the pantries in the communities that have the highest need are receiving the food they need.”
The organization will continue fundraising, seeking food donations from local grocers and purchasing food when necessary to help fill the gaps, Perry said.
“We are considering all options to stand up in a moment of crisis and also to consider what is the food bank of the future,” Perry told the Crusader.
The Food Depository is also taking its work directly into neighborhoods through its Longest Communal Table events, where residents receive meals, learn about available resources and participate in conversations about solutions to hunger.
After Perry’s appearance at Rainbow PUSH, volunteers hosted a Longest Communal Table on South Kildare Avenue between West Madison Street and Washington Boulevard near New Mount Pilgrim Missionary Baptist Church, headed by the Rev. Dr. Marshall Hatch.
Perry said approximately 300 people received food while participating in conversations about ending hunger and learning where families can obtain free food.
Another Longest Communal Table is scheduled for Wednesday, September 30, from 5:30 p.m. to 7:30 p.m. between 65th and 66th streets in Ald. William Hall’s 6th Ward.
The neighborhood outreach comes as the report shows hundreds of thousands of Chicago households remain unable to meet their food needs, even when some assistance is available.
About 128,000 households, or 11 percent, are food insecure and receive no food assistance. Another 289,000 households, or 25 percent, receive assistance but still do not have enough food.
Approximately 124,000 households receive assistance and are considered food secure, while about 631,000 households meet their food needs without assistance.
The numbers underscore the limits of treating hunger solely as a question of food distribution. Families are being squeezed by grocery prices, housing, health care and other expenses while some forms of federal assistance have become harder to obtain.
For Black Chicago households, the report shows the burden is especially pronounced: nearly two-thirds of those surveyed experienced some level of food insecurity.
Perry said the Food Depository will continue expanding partnerships with neighborhood organizations and exploring ways to provide food in communities where access remains limited.
She said residents themselves must be the “driving forces” in determining how organizations respond.
For the Food Depository and its community partners, the challenge is both immediate and long term — getting food to families who need it today while addressing the economic and policy conditions contributing to hunger across Chicago.
Based on reporting by Gary Crusader.
Black Press
Poll: Becerra Widens His Lead Over Hilton; Californians Split on Wealth Tax
A new Public Policy Institute of California poll shows Democrat Xavier Becerra leads Republican Steve Hilton by 22 points in California’s governor’s race, with 60% of likely voters supporting Becerra compared to 38% for Hilton. The September survey also reveals Californians are closely divided on a proposed one-time tax on billionaires, with 52% of likely voters in favor of Proposition 40. Affordability issues are a major factor for voters. Read more to learn about the poll’s additional findings on voter sentiment.
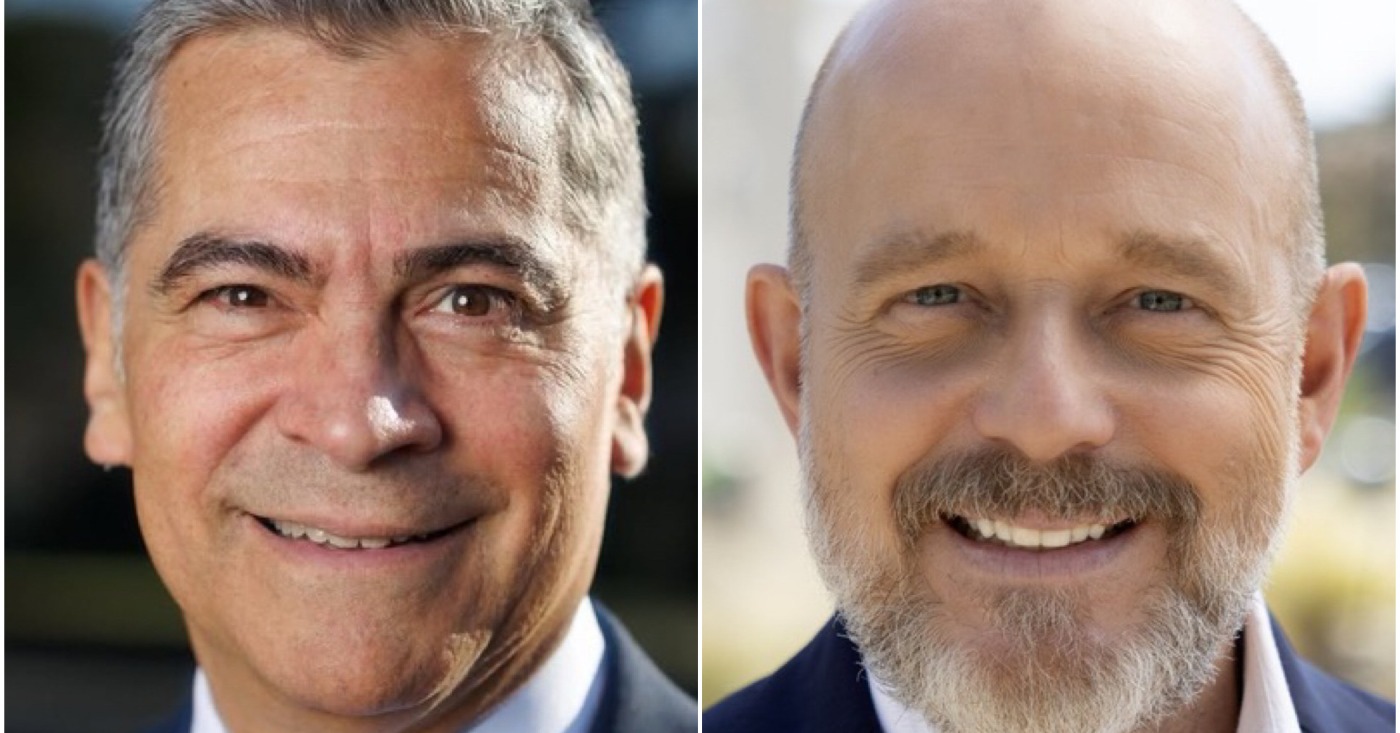
Democrat Xavier Becerra holds a 22-point lead over Republican Steve Hilton in California’s governor’s race, while voters remain closely divided over a proposed one-time tax on billionaires, according to a new Public Policy Institute of California poll.
The September PPIC survey found that 60% of likely voters support Becerra, compared with 38% for Hilton. His lead is actually narrower than it was in July, when he led Hilton 61% to 36%.
Becerra leads among independent voters, with 57% supporting him compared with 38% for Hilton. Party loyalty remains strong, with 93% of Democratic likely voters backing Becerra and 92% of Republicans supporting Hilton.
Hilton leads in the Central Valley, where 52% of likely voters support him compared with 46% for Becerra.
Affordability remains a major factor: 65% of likely voters say candidates’ plans to address cost-of-living issues are “very important” to their vote.
“Affordability continues to be top of mind for Californians when considering their choice for governor,” said Mark Baldassare, PPIC Statewide Survey director and Miller Chair in Public Policy.
The poll also found a narrow split over Proposition 40, a proposed one-time tax of up to 5% on taxpayers with assets exceeding $1 billion. Fifty-two percent of likely voters said they would vote yes, while 46% said they would vote no.
Support for the wealth tax varies sharply by party. Seventy-two percent of Democrats favor Proposition 40, compared with 46% of independents and 21% of Republicans.
Two competing measures also drew majority support. Fifty-one percent back Proposition 41, while 54% support Proposition 42, both of which could affect the wealth-tax proposal.
The findings come as Californians express broader frustration with the state’s political direction. Seventy-one percent of likely voters expect bad economic times in California over the next year.
“Californians are clearly grumpy and aren’t enamored with any particular political party or movement,” Baldassare said.
The survey interviewed 1,745 California adults, including 1,103 likely voters, from Sept. 4-10. The margin of error for likely voters is plus or minus 3.8 percentage points.

COMMENTARY: Battling Black Voter Distrust

Why Black Artists Struggle to Sell Tours

COMMENTARY: Property Is Power! What Is a Gift of Equity and What Could It Mean for Black America?

Consumers and States Awarded $694 Million After Predatory Auto Lender Settles Lawsuit

From Ma Rainey to AI: New Technology Amplifies an Old Fight over Artist Control

News Observer Weekly — September 30, 2026 | Top 5 Stories of the Week

TILGHMAN: Why Parents of Children with IEPs Should Know Their School Bus Driver

AI safety, accountability, and the headlines everyone is talking about.

AI safety, accountability, and the headlines everyone is talking about. 📱

Jamal’s Take: Cowboys’ Devastating Loss … Coaching Blunders & Key Injuries Cost Them

Women Learned Their Jail Strip Searches Were Recorded. Their Outrage Changed the Law

Black Americans Have Doubts About the U.S. Food System

Latest Massacre in Haiti Reveals Cruelty U.S. Deportations

When Praises Go Up: SUGC Nominated for Prestigious Stellar Award.

Booked and Unbound: The Legacy of Black Women’s Literary Circles

U.S. Sole Nation to Oppose U.N. Resolution Correcting Africa’s Size on World Maps

Outnumbered: Elbert Cox’s Equation for Greatness

Prostate Cancer is Twice as Likely to Kill Black Men. Talking to Your Doctor Could Help Save Your Life

COMMENTARY: Big Mama Said ‘Don’t Let Grief Break the Bank’

U.S. Open Influencers Spark Backlash over Ring Lights, Filming as Gauff and Osaka Speak Out
News Observer Weekly — September 30, 2026 | Top 5 Stories of the Week
AI safety, accountability, and the headlines everyone is talking about.
AI safety, accountability, and the headlines everyone is talking about. 📱
Jamal’s Take: Cowboys’ Devastating Loss … Coaching Blunders & Key Injuries Cost Them

Curry’s Impact: How He Revolutionized NBA Defense & Recruiting #shorts

Inspire Through Action: Young Kings & Queens Learn! #shorts

2027 VW Atlas Airconsole Games

2027 VW Atlas Harman Kardon Audio System

Steph Curry: Black Men, White Supremacy & Embodied Logic #shorts

DC Housing Finance Agency (DCHFA) on Resources for Homeowners | Let’s Talk
-
 Black History1 week ago
Passing for White, Fighting for Black America: The Courage of Walter White
-
 Black History1 week ago
The Youngest American Killed in the Vietnam War
-
 Sports1 week ago
NFL: Week Two Recap | Jalen Hurts did not fold; Caleb Williams exits game with injury
-
 Black Press1 week ago
Mayor Lee Announces $1 Million Kaiser Permanente Grant for Pilot Program to Address Homelessness, Clean Up Public Spaces throughout Oakland
-
 Black History3 days ago
Remembering Chauncey Bailey as Student Journalists Face Threats to Truth-Telling
-
 Art1 week ago
Peter Magubane: a Camera Against Apartheid
