Auto
Aftermarket Auto Parts Breathe New Life into Older Cars
BLACKPRESSUSA NEWSWIRE — Thinking about keeping your old car due to today’s exorbitant new car prices? Discover how aftermarket auto parts can help keep your existing ride functional.


From giving owners the opportunity to solve obsolescence issues related to discontinued parts to providing them with cost-effective repairs, these are some of the primary ways aftermarket auto parts breathe life into older or broken-down vehicles. They also offer upgrades that help boost vehicle reliability, comfort, and performance.
With those benefits, it’s no wonder the aftermarket car parts industry is an economic powerhouse. A report from Mordor Intelligence shows that in the United States alone, the market’s estimated size was $238.75 billion in 2026, a figure it projects to grow to $292.27 billion by 2031.
What Are Aftermarket Auto Parts?
Aftermarket automotive parts are accessory or replacement parts made by a third-party company, not the vehicle’s or part’s original equipment manufacturer (OEM). As they’re often widely available and more affordable, many consumers use them as an alternative to dealer-carried OEM parts.
Indeed, automotive aftermarket industry newsletter AftermarketMatters.com reported on the recent survey, “Automotive Aftermarket Pulse 2025,” which found that 57% of consumers now prefer independent aftermarket parts over OEM ones.
Are OEM Parts Still Better Than Aftermarket Auto Parts?
The primary difference between OEM and aftermarket performance parts or replacement components is that the former is the official recommendation of the company that made the vehicle. They’re usually the same parts originally installed in the car when it first rolled off the assembly line.
Still, OEM parts are not always better than high-quality aftermarket automotive products. Some aftermarket parts can have the same quality as high-performance parts manufactured by the OEM.
You can even sometimes find aftermarket parts identical to the OEM ones, with the components coming off the same assembly line. In this case, the supplier sells the OEM part in an aftermarket box for much less than the one labeled “Genuine” OEM.
How Do Aftermarket Auto Parts Breathe New Life Into Older Cars?
Whether you wish to restore a car with parts that have already become obsolete or you just want to extend the life of your current ride due to budgetary reasons, aftermarket auto parts can help. They can even aid in making cars more reliable, comfortable, and better-performing.
Solving Obsolescence Issues
Automakers usually stop manufacturing parts for discontinued models after several years, depending on warranty obligations and market demand. If you have an old car you want to fix or restore but can’t due to obsolescence concerns, consider looking into aftermarket parts.
Aftermarket part makers often step in to bridge inventory gaps, even for discontinued models.
Providing Cost-Effective Repairs
Regardless of the car repairs you need, you’ll most likely find the aftermarket auto body parts, engine components, or suspension pieces you require. Not only are they more widely available, but they’re also typically cheaper than OEM parts.
As Diesel World Magazine points out, the price of OEM parts can be 50% to 100% higher than aftermarket ones.
With aftermarket parts being your ticket to more cost-effective repairs, you can use them to your advantage and breathe new life into your ride. With high-quality, properly installed aftermarket components, you can make your vehicle roadworthy again for less than what you’d otherwise pay if you went with all OEM replacement parts.
Offering Valuable Reliability, Comfort, and Performance Upgrades
If your car is a base or lower-level trim, it may have parts made of basic or lower-end materials (e.g., hard plastics or fewer grease fittings in suspension parts). Replacing these with aftermarket parts made of upgraded materials can help slow down wear and tear or fix known defects.
You can, for example, swap out plastic parts with metal components or get suspension parts with more grease fittings.
Many aftermarket part makers also make products designed to meet, even exceed, modern creature comforts and are compatible with older cars. You can fit a vintage car, for instance, with a modern, aftermarket infotainment system and even an upgraded air conditioning and heating unit.
Many aftermarket auto parts also offer performance upgrades, allowing car owners to change the dynamics of their older car completely.
Adding heavy-duty suspensions and upgrading to electronic fuel injection are two examples of popular enhancements. You can also install modern, energy-efficient LED headlights inside vintage housings.
Frequently Asked Questions
Are There Any Disadvantages to Aftermarket Automotive Parts?
While aftermarket car parts have many notable advantages like cost-effectiveness and wide availability, they’re not perfect and can present several drawbacks. One of these is incorrect fitment.
Since aftermarket parts offer a “universal” fit, they don’t always have the same dimension tolerances as their OEM counterparts. Buying these ill-fitting components can lead to installation headaches or incorrect alignment, both of which can cause issues with handling and tire wear.
Inconsistent quality is another issue car owners should be aware of when buying aftermarket car parts. While many brands make products that exceed original specifications, the cheapest or lowest-budget options may sometimes cut corners.
Such parts can wear and tear much faster and fail early.
How Can You Ensure the Quality of the Aftermarket Car Parts You Buy?
Always do your due diligence when buying aftermarket car parts, which involves careful research of each of your prospective makers/suppliers. Look for third-party quality certifications, such as from the Certified Automotive Parts Association (CAPA).
CAPA is one of the leading certifying organizations within the aftermarket automotive parts industry. It provides testing to verify and ensure aftermarket parts are functionally equivalent to their OEM counterparts.
You should also consider sticking to reputable manufacturers known for their superb engineering. Highly reputable brands usually make hefty investments in their research and development processes, sometimes even manufacturing parts that they supply straight to automakers.
Don’t forget to read verified reviews. They can give you a way to gauge real-world experiences regarding proper fit and part longevity.
Restore Your Car’s Glory With Aftermarket Auto Parts
Properly installed, high-quality aftermarket auto parts can help make your ride roadworthy again by giving you access to more cost-effective replacement parts, even discontinued ones. They can even make your car better by providing reliability, comfort, and performance upgrades.
If you’re looking for more informative guides like this or would like to read up on the latest events in the Black community, we’ve got you covered. Check out more of our recent posts and news articles to stay in the loop.

Auto
Consumers and States Awarded $694 Million After Predatory Auto Lender Settles Lawsuit
WASHINGTON INFORMER — A class-action settlement involving predatory auto lender Credit Acceptance Corporation (CAC) has resulted in $694 million in relief for an estimated 55,000 consumers. Attorneys general from 40 states and the District of Columbia announced the settlement with one of the nation’s largest subprime auto lenders on September 18.
An estimated 55,000 consumers will benefit from a $694 million class-action settlement against a predatory auto lender reached by attorneys general in 40 states and the District of Columbia.
The settlement announced on Sept. 18 with Credit Acceptance Corporation (CAC), one of the nation’s largest subprime auto lenders, will provide the following financial relief for affected consumers:
- $630 million in debt relief for consumers — $388 million to consumers whose cars have been repossessed; the remaining $246 million for those whose vehicles have not been repossessed and will now keep their autos.
- $60 million in restitution to thousands of additional consumers who were misled and lost their cars within months of taking out their loans.
- $15.5 million in reimbursement to each state office that comprised the multistate working group, and the National Association of Attorneys General.
“CAC preyed on consumers in New York and across the nation with false promises of affordable loans, only to exploit them with outrageous interest rates that ruined their credit and cost them their cars,” said New York Attorney General Letitia James, who led the multi-state effort. “While their customers struggled to make payments, CAC made millions. By continuing our case to hold CAC accountable, we secured hundreds of millions of dollars in debt relief and restitution for all those who were taken advantage of by their schemes.”
The lawsuit, originally filed in 2023, alleged that CAC projected, down to the penny, how much money it could extract from borrowers through loan payments, late fees, repossession and auction, debt collection, and wage garnishment, without considering a consumer’s ability to repay their loan, according to James. CAC then offered to split the projected collections with its affiliated dealers.
Low-income borrowers with either low credit scores or little credit history were routinely pushed into purchasing vehicles that were worth far less than their loans. CAC states on its own website: “Approval decisions are typically available in 30 seconds or less, and nearly 80 percent of deals are approved for funding within 24 hours.”
Further, CAC misstated key terms on loan agreements, including the principal and interest amounts, and did not disclose thousands of dollars in credit charges. Although the average loan carried an annual interest rate of more than 38%, other rates reached over 100%. These predatory debt trap loans soon defaulted within 12 or 18 months.
“Credit Acceptance Corporation set car buyers up to fail by making loans it knew they would never be able to afford, and by allowing dealers to inflate the cost of financing agreements with hidden add-ons. As a result, the company profited, even while customers lost their cars and continued to struggle with debt,” said District of Columbia Attorney General Brian L. Schwalb.
Other state officials had similar reactions to the settlement.
“Credit Acceptance Corporation closed its eyes to deceptive origination practices and made predatory, high-cost auto loans that were likely to result in repossession and leave consumers trapped in a cycle of debt,” said California Attorney General Rob Bonta.
Consumers eligible for restitution will be notified by a claims administrator. Consumers with questions about the settlement can call CAC’s customer service number at 800-634-1506.
The settlement also provides additional terms that will free affected consumers from many of the other financial harms inflicted, while other stipulations carry long-term, consumer-friendly reforms.
In the short term, CAC must contact and clearly inform consumers of any products they purchased and offer them a process to cancel those products while keeping their vehicles. It must also notify all affected consumers that their car loan accounts have been closed, no further payments are owed, any lien held has been released, and the certificate of title has been sent. Credit bureaus will also be notified of these actions.
For the next five years, CAC is required to submit written reports that demonstrate how it is complying with all aspects of the consent order. Any failure or shortcomings related to the order will prompt a mandatory remediation plan with details that identify how compliance will be achieved.
Other long-term settlement stipulations that CAC must observe:
- Providing consumers with pre-loan disclosures about the risks of default and the value of the vehicle.
- Limiting a price cap for vehicle prices to no more than 109% of retail book value for certain consumers.
- Implementing procedures that prevent dealers from raising car prices due to creditworthiness or above advertised prices.
Comments in a report released earlier this year by the Center for Responsible Lending showed how consumers with subprime credit scores, most of whom are Black, were left reeling from the effects of predatory car loans.
As Nicole, one participating consumer, noted, “You pay that and nothing, nothing ever changes.”
As CAC faces court-ordered reforms and restitution, Nicole and similar consumers can finally receive well-earned financial fairness.
Charlene Crowell is a senior fellow with the Center for Responsible Lending. She can be reached at[email protected].
Based on reporting by Washington Informer.
Auto
Gubernatorial Candidate Steve Hilton Blasts California New Tire Rules; Newsom Hits Back
Newsom defended the regulations Aug. 19, citing the commission’s projected savings for consumers. “I think it was a good choice,” said Newsom. “Save a billion dollars a year in fuel. Talk about an affordability agenda, that makes sense to me.”
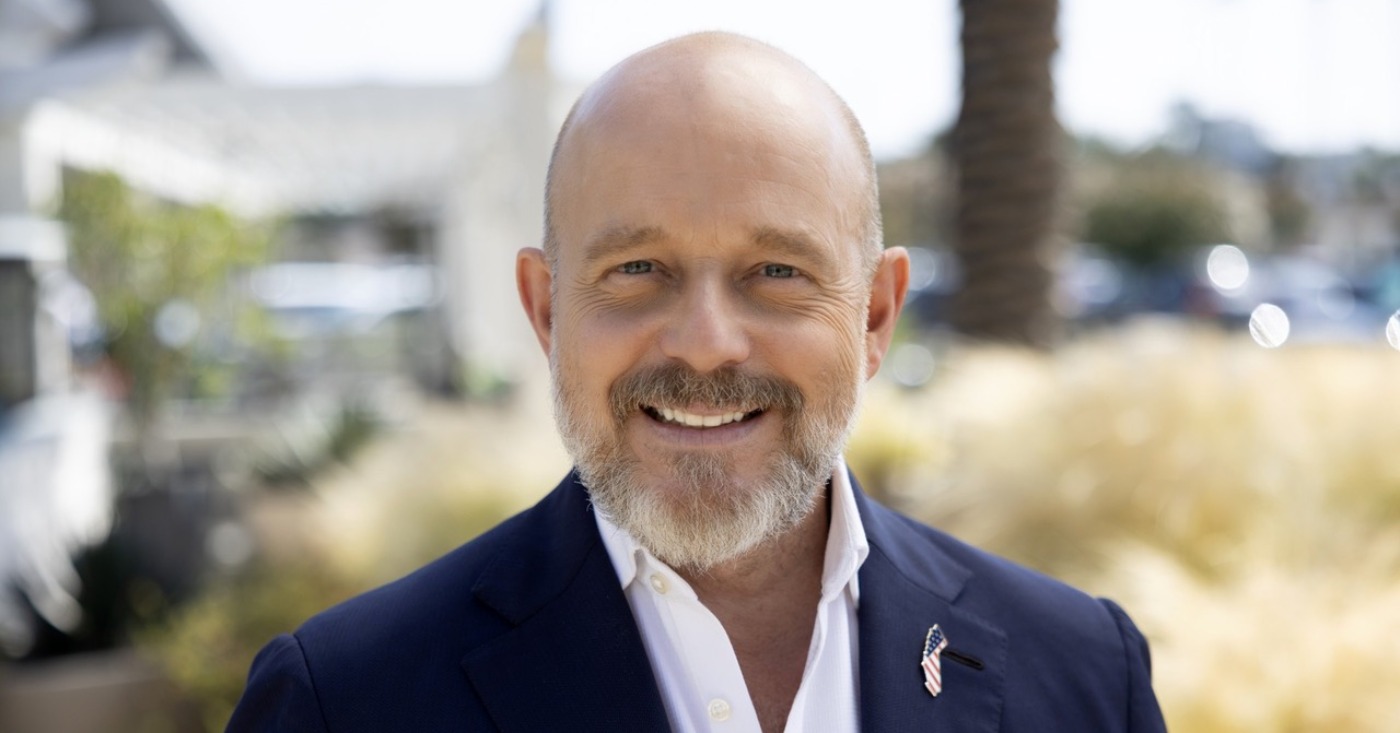
Republican gubernatorial candidate Steve Hilton is criticizing California’s new replacement-tire efficiency standards, arguing they will limit consumer choice and increase costs for drivers.
Gov. Gavin Newsom, however, says the regulations will save consumers money.
Hilton protested the standards Aug. 20 outside the California Energy Commission in Sacramento, where he and supporters chanted, “Hands off our tires.” The commission unanimously approved the regulations Aug. 17, making California the first state to adopt energy-efficiency standards for replacement tires.
“We are done with these bureaucrats and these politicians in our state, making everything so insanely expensive,” Hilton said at the protest.
Hilton said that, if elected governor, he would eliminate or defund the Energy Commission. His opposition to the tire standards is part of his broader criticism of California’s high cost of living.
Newsom defended the regulations Aug. 19, citing the commission’s projected savings for consumers.
“I think it was a good choice,” said Newsom. “Save a billion dollars a year in fuel. Talk about an affordability agenda, that makes sense to me.”
The Replacement Tire Efficiency Program sets limits on rolling resistance, which measures how much energy a tire requires to move along a road. Tires with lower rolling resistance can improve a gasoline-powered vehicle’s fuel economy or extend an electric vehicle’s driving range.
The first phase will take effect in 2029, setting a maximum rolling resistance of 9.1 newtons per kilonewton. A stricter limit of 7.2 newtons per kilonewton will take effect in 2033.
The Energy Commission says the standards will ensure that replacement tires are, on average, at least as energy efficient as those installed on new vehicles. The agency estimates the regulations will save Californians nearly $1 billion annually in gasoline and electricity costs while reducing carbon dioxide emissions by two million metric tons a year.
Some tire manufacturers, however, have raised concerns about the effect on prices and product availability. Goodyear estimates that about 70% of replacement tires currently sold in California would not meet the 2033 standard and argues that the regulations could increase costs for consumers.
The Energy Commission estimates the standards will add about $1.50 to the cost of each tire during the first phase and $6.50 per tire beginning in 2033. The commission projects that a driver with a gasoline-powered vehicle could save about $179 in fuel costs over the life of a set of tires meeting the 2033 standard.
The regulations exempt several specialty products, including competition, winter, used, retreaded, motorcycle and certain off-road tires.
Auto
Rising Car Insurance Rates Are Putting New Pressure on Household Budgets
BLACKPRESSUSA NEWSWIRE — Higher premiums arrive as families already manage rising food, housing, utility, and transportation costs. Many households have little to no room to absorb another monthly increase. A much higher insurance bill may force drivers to delay repairs, reduce savings, use credit, or cut spending in other very important areas.

By April D. Lee
Rising car insurance rates are forcing households to reconsider how much they drive, what coverage they carry, and which expenses can wait. Drivers can ease the pressure by comparing policies, reviewing deductibles, and removing unnecessary costs without giving up essential financial protection.
A routine renewal notice can now disrupt an entire household budget. The national combined average premium per insured vehicle reached $1,438 in 2023, representing a 14.42% increase from 2022, according to data cited by MarketWatch.
Higher premiums arrive as families already manage rising food, housing, utility, and transportation costs. Many households have little to no room to absorb another monthly increase. A much higher insurance bill may force drivers to delay repairs, reduce savings, use credit, or cut spending in other very important areas.
Canceling coverage may appear to offer immediate relief. However, driving without adequate insurance can expose a household to severe financial losses after a crash. A very careful policy review offers a safer way to control costs while protecting income, savings, and essential transportation.
Why Did My Car Insurance Go Up When Nothing Changed?
A clean driving record does not guarantee a stable premium. Insurance companies consider personal driving history, but they also examine broader risks affecting an entire area or group of policyholders.
Repair expenses remain one major factor. Modern vehicles often contain:
- Cameras
- Sensors
- Computers
- Electronic safety systems
A minor collision can damage equipment that requires specialized parts and trained technicians. Insurers may also adjust premiums because of:
- Higher medical expenses
- More expensive replacement parts
- Vehicle theft trends
- Severe weather losses
- Local crash frequency
- Uninsured motorists
- State insurance regulations
The 2026 insurance forecast from Inszone Insurance Services indicates that personal auto premiums may continue rising, although the pace of growth may slow. Claim expenses, labor costs, replacement parts, and legal settlements remain elevated.
Location can influence premiums as much as individual behavior. Dense traffic, regional weather patterns, repair prices, and local theft rates can cause car insurance increases at renewal.
Expired discounts may also raise the bill. A mileage change, new household driver, replacement vehicle, address change, or credit-based insurance adjustment may affect the insurer’s calculations.
Drivers should request a written explanation when a premium changes. An incorrect mileage estimate, missing discount, or outdated vehicle classification could increase the cost unnecessarily.
How Can I Lower My Car Insurance Rates Without Losing Coverage?
Start by requesting a new car insurance price quote from several carriers before the existing policy renews. Insurance companies use different formulas to measure risk. Two companies may offer very different prices for nearly identical protection.
Compare quotes using the same:
- Liability limits
- Deductibles
- Vehicle information
- Driver information
- Optional benefits
- Coverage periods
A lower quote may provide less protection. Review every limit and exclusion before changing carriers.
Drivers may also reduce premiums by increasing a deductible. However, the deductible must remain affordable. A $2,000 deductible offers little help when a household cannot produce $2,000 after a crash.
Usage-based insurance may benefit people who drive carefully or travel fewer miles. Telematics programs may track speed, braking, mileage, and driving times.
Higher Premiums Are Reshaping Household Decisions
Vehicle ownership now consumes a significant share of household income. LendingTree estimates that Americans with active auto loans spend $12,841 each year on vehicle ownership. The amount equals about 15% of the median household income.
Insurance accounts for an average of $2,277 per year within those ownership expenses, according to the same LendingTree study. Average insurance spending has increased 37.5% since 2021.
A premium increase can affect more than transportation. Families may reduce grocery spending, emergency savings, retirement contributions, debt payments, or medical care to keep a vehicle insured.
Repair Costs and Vehicle Choices Keep Rates Elevated
Parts, labor, medical treatment, and legal settlements continue to increase claim expenses. Weather losses and theft add pressure in many markets. Vehicle selection can also affect insurance expenses before a buyer signs a loan.
Certain vehicles cost more to repair or replace. Powerful engines, luxury parts, theft risk, and advanced technology can increase premiums.
Ways to Protect Coverage While Cutting Costs
A focused insurance review can produce meaningful savings without leaving the household exposed. Drivers can take several practical steps:
- Compare equal limits across at least three insurers.
- Ask which discounts are active or expiring.
- Remove duplicate roadside assistance benefits.
- Review rental reimbursement limits.
- Update annual mileage accurately.
- Check insurance costs before buying another vehicle.
- Save the full deductible before increasing it.
- Keep liability limits strong enough to protect household assets.
Liability coverage deserves special attention. A serious collision can create expenses that exceed a basic policy’s limits.
Guidance from a Phoenix car accident lawyer may become relevant when injuries, disputed fault, or an uninsured driver complicate a claim.
Frequently Asked Questions
Can Insurers Raise Rates Even When a Driver Has No Accidents?
Yes. A renewal premium can change because of:
- Statewide rate filings
- Regional claims
- Repair inflation
- Vehicle theft
- Severe weather
- Medical expenses
- A new insurer pricing model
A driver’s personal history remains important, but premiums also reflect losses within a wider insurance pool. Drivers should request an explanation and verify every detail on the policy. An incorrect address, annual mileage estimate, vehicle classification, or missing discount can affect the premium.
Is Dropping Full Coverage a Good Way to Save Money?
Dropping collision or comprehensive coverage may make sense for some older vehicles. Drivers should first consider whether they could replace the vehicle after:
- Theft
- Flooding
- Vandalism
- An at-fault crash
Lenders often require physical damage coverage on financed vehicles. Liability-only insurance does not pay to repair or replace the policyholder’s car. Compare the yearly savings with the financial loss the household could absorb.
What Role Can Regulators Play in Insurance Affordability?
State insurance departments review rate filings under rules that differ by state. Consumers can contact regulators when an increase appears incorrect or cannot be explained. Policy discussions also examine:
- Market competition
- Pricing transparency
- Consumer protections
- Regulatory authority
Take Control of Car Insurance Rates Before the Next Renewal
Rising car insurance rates deserve the same attention as a loan payment, utility bill, or housing expense. Drivers should begin shopping before renewal, compare policies with equal coverage, review available discounts, and choose deductibles they can afford.
Explore our other guides and articles for more practical news, consumer information, and financial guidance.
Art
Milestone Reached, Legacy Remains
ST. LOUIS AMERICAN — Collier Brothers Auto Body, a historic Black-owned business in St. Louis, recently celebrated its 80th anniversary before closing its doors on June 1. Co-owner Craig Collier had expressed a goal five years ago to reach this milestone after the shop’s 75th anniversary.

Mural honors Collier Brothers Auto Body’s 80 years of Black business history
Collier Brothers Auto Body reached the milestone its owners hoped to reach.
Five years ago, as the historic Black-owned St. Louis business celebrated its 75th anniversary, co-owner Craig Collier said he hoped to keep the shop going another five years — long enough to reach 80 years.
It did.
Collier Brothers, founded in 1946 and operated by generations of the same family, marked its 80th year before closing its doors June 1.
The family and community celebrated that history Saturday with the Common Ground Community Car Show & Block Party at the shop’s longtime home, 4561 Delmar Blvd. The event included the unveiling of a mural honoring the business.

Brothers Raymond Collier Sr. and Elie “Bud” Collier founded the business in March 1946 after returning from military service. Each contributed $350 in mustering-out pay — money provided to service members leaving the military — to help launch the shop. Raymond had served in the Navy and Elie in the Army.
In segregated St. Louis, the brothers established their business in Mill Creek Valley, the predominantly Black neighborhood that was later demolished as part of the city’s urban renewal program.
Collier Brothers moved five times before settling in 1958 at 4561 Delmar, where it would operate for nearly seven decades.
By the 1970s and ’80s, the shop was thriving.
“I remember my dad coming down here, seeing it really full,” Craig Collier, Elie Collier’s son, told The St. Louis American in 2021. “Back in the ’70s, you know, you couldn’t even walk inside the shop; it was just back-to-back cars.”
Collier had been coming to the shop since he was 3 years old and knew by about age 11 that he liked working with cars.

His cousin Wayne Jackson, Raymond Collier’s grandson, took a different path. Jackson spent 10 years working with computers for the St. Louis Metropolitan Police Department before joining the family business.
The cousins officially took over the shop in 1996, although the founders remained involved for years afterward.
Raymond Collier continued working well into his 70s before his death in 2014. Elie Collier, who devoted more of his later years to ministry, died in 2015.
As the decades passed, the business changed. Competition increased, and the shop was no longer packed with cars as it had been during its busiest years.
By its 75th anniversary in 2021, Collier and Jackson were considering what would happen when they were ready to step away.
“That’s what we’re kind of in limbo about,” Jackson told The American at the time. “They have a desire, but we haven’t mapped it all out yet. We haven’t decided what we’re doing. We’re trying to work on a succession plan.”
One possibility was Jackson’s daughter, Sydney, who was then finishing college at the University of Nevada, Las Vegas. With the COVID-19 pandemic keeping her in St. Louis, she was helping answer phones at the shop and had begun thinking seriously about its future.
“It’s always been a family business,” she said in 2021. “We want to uphold that culture and the legacy that was set there by our forefathers.”
She also acknowledged that taking over an auto body shop had not been part of her original plans.
“I am not a business person,” she said. “But I don’t want to let the legacy go down.”
Craig Collier, meanwhile, was thinking about how much longer he could physically continue working in auto body. He told the St. Louis Post-Dispatch in 2021 that he hoped the business could make it another five years and reach its 80th anniversary.
Sydney Jackson declined to discuss the circumstances surrounding the shop’s closure on Saturday.
The shop’s history received renewed attention through the Missouri History Museum’s “Mill Creek: A Black Metropolis” exhibit, which included Collier Brothers in its examination of the once-thriving Black neighborhood.
Saturday’s celebration included the unveiling of a mural by artist Jen Everett. The mural was commissioned by Delmar Main Street through a public arts initiative funded by a grant from the City of St. Louis Community Development Administration.

The event comes as the Delmar corridor continues recovering from the May 2025 tornado, which caused extensive damage in North St. Louis and other parts of the city.
Sydney Jackson, who hosted Saturday’s event, said she hoped the car show would help bring people together and support efforts to revitalize the corridor.
“There’s community here, there’s love here, there’s entrepreneurial possibilities here,” she said.
Jackson said Delmar continues to represent two different experiences.
“There’s two different experiences going on on the North and the South side of the street at this point in history,” she said. “I think we need to realize that we both have value.”
Jackson said that means making space for both sides and “encouraging those on the North side to remember that they matter too.”
St. Louis American visual journalist Lawrence Bryant contributed to this report.
The post Milestone reached, legacy remains appeared first on St. Louis American.
Based on reporting by St. Louis American.
Auto
Predatory Auto Lending Exploits Black Consumers
CHICAGO CRUSADER — A significant majority of American households depend on personal vehicles. While new cars average $49,307 and used cars $25,918, Black and other consumers of color face additional financial challenges due to discriminatory and predatory practices in auto sales and financing.

Nearly 92 percent of American households rely on a personal vehicle to manage their daily lives. Consumers shopping for a vehicle in May learned that the average cost of a new car was $49,307, and that used cars averaged $25,918, according to Cox Automotive.
But the high price of vehicles is not the only financial challenge confronting Black and other consumers of color. Discriminatory and predatory practices in the sale and financing of cars, including predatory lending, have pushed millions of buyers into longer and higher priced loans.
A study by the National Fair Housing Alliance found that non-white test shoppers were given more expensive financing 62.5 percent of the time compared to white testers with equivalent or worse credit. Similarly, another recent independent study by the Century Foundation concluded that Black, Hispanic, and American Indian borrowers are given higher interest rates on auto loans across all credit tiers. Research published by the Federal Reserve found Black borrowers disproportionately pay the highest interest rate mark-up, resulting in more than $3,000 in additional interest over the life of the loan due to predatory lending practices.
Now a new report released by the Center for Responsible Lending (CRL) found that the terms of predatory loans as well as dealers and lenders conniving to drive up costs – not the consumers’ willingness to pay – made delinquency and default more likely. These tactics limit alternatives borrowers can pursue to lower their payments. This conclusion came through a series of consumer focus groups with subprime credit scores, most of whom are Black, reeling from the effects of predatory car loans.
High-pressure tactics, misleading claims about vehicle features or conditions, and aggressive upselling of overpriced add-ons and services together obscured the true cost of the vehicle and prevented consumers from making informed decisions. Beyond auto sale, dealer financing exposes consumers to interest rate markups, hidden fees, and unaffordable loan terms.
Nicole, a Black woman in her early 50s who lives in Minneapolis, Minnesota shared her personal story of urgently needing a vehicle as she went through a separation in which her former spouse kept their car.
A full-time employee at a nonprofit organization focused on ending homelessness, she earns less than $50,000 a year. She took out a loan for $19,000 with an interest rate of 24 percent and a 48-month term. In addition to the inflated sales price of the vehicle, the dealer included a $2,000 warranty and the lender rolled over a previous loan for a repossessed vehicle that significantly increased the total financing for Nicole.
Shortly after the sale, Nicole discovered the car lacked heat and had a failed engine, fuel pump, and water pump — all undisclosed problems requiring costly repairs that were not fully covered by the warranty. She now owes more on her car than it’s worth but still needs a way to get to work. Making payments has been a struggle and on a few occasions, the car has been taken away due to late payments.
“You pay that and nothing, nothing ever changes,” Nicole shared. “And even when it reports on the credit bureau, it says that I’m still past due, like, 31 payments, and they’ve come, they’ve taken the truck. I pay when I’m past due, and they give it back to me. So, it’s a vicious cycle.”
A portion of CRL’s report explains the costly and limited options lenders provide borrowers who fall behind on payments:
“A deferment lets a borrower skip a payment, but the skipped amount is added to the end of the loan along with additional interest. Lenders often describe deferments as just moving a payment to the end and does not disclose the true costs of doing so. However, the accumulating interest means borrowers end up paying more than the deferred payment and may become even more underwater as the car depreciates while the loan balance grows.”
“Isabelle,” a journalist in Florida using a pseudonym, related her experience with deferment:
“The problem with that is like they charge a daily interest, and you never catch up. Because I did that a couple of times, I was paying my car payment and then the payoff amount would not change at all, because the interest is so high, plus all those daily fees and everything. So, I didn’t have a choice. I had to do it. I do not recommend [it] if you can stretch and maybe borrow some money from family, friends, or whatever, because it’s better than to do that.”
Many auto lenders have also turned to technology that remotely disables vehicles if a borrower falls behind on payments. These “kill switches” can put drivers in physical as well as financial risk.
Monica, another borrower, told of the lender disabling her car while she was driving:
“I forgot that they have the GPS thing installed. My car is jerking and I’m on the side of the road. And so when I called roadside, they were like, we can’t help you. It’s this [start interrupter device] I’m like, you couldn’t send me an email? Like, you see my payment history. What if I was on the freeway, and not only just a regular street?”
CRL urges the Federal Trade Commission, Consumer Financial Protection Bureau, and states to establish several consumer protections, including limits on how much lenders can charge.
“This report shows how the advantages auto dealers and lenders have over consumers result in exploitation,” noted Lucia Constantine, report co-author and a CRL senior researcher. “Our government must establish guardrails to protect consumers — like it did in the mortgage market.”
Based on reporting by Chicago Crusader.
Auto
Starting This Summer, California Car Buyers Can Get an Instant $3500 Off the Cost of Electric Vehicles
OAKLAND POST — Beginning later this summer, eligible Californians can receive a $3,500 rebate on new zero-emission vehicles with a manufacturer’s suggested retail price of up to $50,000. Buyers purchasing qualifying used electric vehicles priced at up to $25,000 can receive a $1,750 rebate. The rebate will be applied directly at participating dealerships, allowing buyers to receive the discount immediately instead of waiting for reimbursement.

California residents purchasing their first zero-emission vehicle will soon be eligible for an instant rebate of up to $3,500 under a new state program aimed at making electric vehicles more affordable.
Gov. Gavin Newsom signed Senate Bill (SB) 168 on July 16, creating the MyFirstEV program as part of California’s 2026-27 state budget. The initiative dedicates $135.5 million in state funding for point-of-sale rebates, which participating automakers will match dollar for dollar. State officials said the combined investment will provide $270 million in savings for first-time electric vehicle buyers.
Beginning later this summer, eligible Californians can receive a $3,500 rebate on new zero-emission vehicles with a manufacturer’s suggested retail price of up to $50,000. Buyers purchasing qualifying used electric vehicles priced at up to $25,000 can receive a $1,750 rebate. The rebate will be applied directly at participating dealerships, allowing buyers to receive the discount immediately instead of waiting for reimbursement.
“With our new instant rebate program for electric vehicles, we’re making it easier for families to drive clean, breathe clean, and keep more money in their pockets,” Newsom said in a statement.
The MyFirstEV program is part of a broader $600 million investment in California’s clean transportation economy included in the state budget. The funding package also provides $150 million for the Community Air Protection Program, $19.8 million for the Clean Cars 4 All program for lower-income residents, $35 million for clean off-road equipment through the Air Quality Improvement Program, $135.5 million for the Clean Truck and Bus Voucher Incentive Project, and $130 million for the Carl Moyer Program to replace older heavy-duty engines with cleaner alternatives.
According to the governor’s office, the transportation investments are funded through Cap-and-Invest revenue and smog-abatement fees while maintaining a balanced state budget.
California continues to expand its zero-emission transportation network. The state surpassed 2.5 million cumulative zero-emission vehicle sales earlier this year, exceeding its original goal of 1.5 million sales by 2025. Officials also reported that California has more than 200,000 public and shared electric vehicle charging plugs statewide, in addition to an estimated 800,000 home charging stations.
Secure growth by funding business expansion without taking on bad debt
Save money on storm damage repairs by addressing your property hurricane risk early in the season

Sunset Loft – The Crystal

HISD takeover “diminished, degraded, destroyed” schools – Citizen commission report

Everything You Need to know before you Vote

From Doubts to Calling: My Wife Saved My Career #shorts

HBCU Homecoming: A never-miss annual tradition

How Community Builds the Confidence to Start a Business #shorts

2026 Silverado High Country What $82,004 Gets Right—and Wrong

WCCUSD Joins Statewide Organic School Food Purchasing Cooperative

The Youngest American Killed in the Vietnam War

Passing for White, Fighting for Black America: The Courage of Walter White

OP-ED: Haiti TPS: Have We Lost Sense of Humanity?

OP-ED: If AI Is the New Language of Power, Then NAN Wants Black Communities Fluent

OP-ED: How Does Your State Rank for Pre-K?

Henry O. Flipper: A Trailblazer at West Point and Beyond

Asm. Smallwood-Cuevas’s Bill Repealing ‘Racist’ CalWORKs ‘Man-in-the-House’ Rule Clears Legislature

NFL: Week Two Recap | Jalen Hurts did not fold; Caleb Williams exits game with injury

Remembering Chauncey Bailey as Student Journalists Face Threats to Truth-Telling

California Legislature Sends Historic Native American Apology Bill to Gov. Newsom’s Desk
Sunset Loft – The Crystal
HISD takeover “diminished, degraded, destroyed” schools – Citizen commission report
Everything You Need to know before you Vote
From Doubts to Calling: My Wife Saved My Career #shorts
HBCU Homecoming: A never-miss annual tradition
How Community Builds the Confidence to Start a Business #shorts
2026 Silverado High Country What $82,004 Gets Right—and Wrong

Hennepin Commissioner Marion Greene: Three county programs helping Latino communities

DNC member Ron Harris: DHS raided Ilhan Omar’s home

Hennepin Commissioner Angela Conley: Eliminating disparities-reparative justice and homeownership
-
 Black Press1 week ago
Zakiya Jendayi Arrested, Locked Out of Home by Sheriff’s Deputies
-
 Black Press1 week ago
A $2.1 Trillion Wellness Industry Never Built a Daily Practice for Black Children. So This Atlanta Family Did.
-
 Art1 week ago
Montclair Brewery: Brewing Culture, Community, History
-
 BlackPressUSA6 days ago
Latinas Deserve Equal Pay. Unions Help Make It Happen.
-
 Black History1 week ago
Listening as a Lifeline: A Doula’s Witness to Black Maternal Health
-
 Black Press1 week ago
COMMENTARY: But God!
