Business
White House Proposes $9.2 Billion Cut in Education Funding


By Charlene Crowell (NNPA Newswire Columnist)
No one ever said that higher education wouldn’t cost money. Across the country, tuition is steadily rising and students are taking longer to pay off their student loans.
Today, 44 million consumers share $1.4 trillion in borrowed student debt – more than double what it was in 2008. On average, graduating seniors with a bachelor’s degree begin their careers with about $30,000 in student loans, while graduate students are almost assured of incurring six-figure student debt.
All of these financial burdens have been acquired against a backdrop of an increasingly competitive global economy. The 21st Century marketplace is also dependent upon a highly-skilled workforce. Gone are the days when manufacturing could provide a steady and comfortable living. From steel to textiles and more, global competition requires America to work smarter and harder.
So why would the Trump Administration propose a $9.2 billion cut in education?
Over the next decade, the White House wants to ‘save’ $143 billion from college loan programs, including an end to $26.8 billion in subsidized loans. Currently, Pell Grants, designed to assist low-income students, are capped at less than $6,000 per scholastic year despite the average cost of tuition at a public college for its own state students approaching $10,000 per year.
Here’s one White House explanation on how less access to higher education going to help the nation’s ability to remain economically competitive.
“We’re no longer going to measure compassion by the number of programs or the number of people on those programs, but by the number of people we help get off of those programs,” said White House Budget Director Mick Mulvaney during a May 23 press briefing.
It seems like the White House is really averse to more Americans receiving a higher education at a time when college costs and its resulting debt are on an upward trajectory. Certainly, education budget cuts will not ‘make America great again’.
Two days later and on the floor of the U.S. Senate, a diverging view was spoken, “Let’s give struggling students a fair chance,” said Illinois’ Senator Richard Durbin.
“We are seeing an increase in the wealth gap between college graduates with student debt and those without student debt”, Durbin continued. “The burdens of student debt are threatening the notion that being college-educated is enough to get ahead.”
Sen. Durbin went on to share the story of a Chicago constituent, the first in her family to attend college, who appealed to his office for help. The majority of the former student’s debts totaling $120,000 were private loans with high interest rates and monthly payments that were just as costly. The student also felt she had no chance of financial improvement due to an ill-conceived enactment of a bill that prevented such debts being discharged in bankruptcy.
Since 2005, student loan debt, unlike other types of unsecured debt cannot be a part of a bankruptcy filing. In other words, it’s the kind of debt that could potentially follow borrowers to the grave.
The Fairness for Struggling Students Act of 2017 (S. 1262), introduced by Sen. Durbin and co-sponsored by 11 other Senators would allow financially struggling borrows to discharge private student loans in bankruptcy. The law is anticipated to relieve high-cost private loans that seldom come with many of the flexible repayment terms offered by federal ones. Some private student loans come with variable interest rates, high origination fees and scant – if any – repayment options.
Already the bill has attracted the support of a large coalition of educational, student, civil rights and consumer organizations that include: the United Negro College Fund (UNCF), NAACP, the American Federation of Teachers, the Empire Justice Center, National Association of Student Financial Aid Administrators, and the Center for Responsible Lending (CRL).
According to the Consumer Financial Protection Bureau (CFPB), in 2012, at least 850,000 private loan borrowers were in default in the amount of $8 billion. Two years later in 2014, CFPB analyzed more than 5,300 private student loan complaints filed between October 2013 and September 2014. That analysis found that the lack of affordable repayment plans, not a disregard for the debt, drove many borrowers to default.
Defaulting on a private student loan has the potential to bring even more financial calamity to borrowers. In some cases, the entire loan balance may become due in full, immediately. Loan defaults can also lower consumers’ credit profiles, preventing some borrowers from passing a background check for a job, obtaining housing, or accessing low interest forms of credit.
Additional CRL research has found that:
• Four years after graduation, Black students with a bachelor’s degree owe almost double the debt their white classmates owe; and
• While for-profit college enrollment represents 9.1 percent of all college students, these schools generate over 35 percent of all students who default on their loans; and
“Quality education is an investment – not a cost – to our nation’s future, noted Whitney Barkley-Denney, a CRL policy counsel. “Its policies and practices must assure student success while minimizing costly debt errors that become unnecessary burdens,”
“When students fall off a financial cliff, they should be able to discharge their private student loan debt in bankruptcy – just like people can with other kinds of debt,” said Senator Elizabeth Warren. “Banks fought hard more than a decade ago to exempt student loan debt from bankruptcy protections, and now we’ve seen the consequences: too many students are crushed by debt with no chance for a new start.”
Charlene Crowell is the Center for Responsible Lending’s communications deputy director. She can be reached at [email protected].







Black History
Listening as a Lifeline: A Doula’s Witness to Black Maternal Health
OAKLAND POST — Maternal mortality and pregnancy-related mortality use different time frames and methods and are not interchangeable. Finalized 2024 CDC data recorded 649 maternal deaths nationally. The overall rate was 17.9 deaths per 100,000 live births, but for non-Hispanic Black women it was 44.8, compared with 14.2 for White women and 12.1 for Hispanic women.
Word Count: 1058
Note: Client A, B & C, names are withheld for privacy; these accounts reflect my recollections as theirDoula.
Client A rocked her hips on a birthing ball, surrounded by pale wood and warm textiles in a softly lit Scandinavian-style office. I was her doula through a Southern California maternal health company combining nurse-led care, technology, and wraparound support.
She was a healthy Black woman in her thirties. Her baby girl was doing well; her partner took notes as we discussed labor and advocacy.
Then we turned to their chosen hospital. I knew it well—and remembered a phrase from another client’s experience: “Policy of Sovereignty.”
Client B had been told she needed a repeat cesarean as a precaution, though the reasoning was unclear. Her obstetrician, who performed her first cesarean two years earlier, had assured her throughout pregnancy that she was healthy, healed, and ready for a vaginal birth. We asked staff to review her chart, consult her obstetrician, and reconsider immediate surgery. Instead, they invoked the “Policy of Sovereignty.”
The physician on duty, we were told, had final authority, regardless of her established care plan. I asked whether an ultrasound or reassessing the baby’s position could offer clarity. Cesareans can be lifesaving. But were Client B’s history, informed consent, and circumstances guiding this decision—or was routine overriding individualized care? We kept asking for her obstetrician. Beneath every request was a deeper question: Was she being heard?
The Numbers Behind the Stories
Statistics arrive in clean columns. The experiences behind them do not.
Maternal mortality and pregnancy-related mortality use different time frames and methods and are not interchangeable. Finalized 2024 CDC data recorded 649 maternal deaths nationally. The overall rate was 17.9 deaths per 100,000 live births, but for non-Hispanic Black women it was 44.8, compared with 14.2 for White women and 12.1 for Hispanic women.
In California, Black birthing people experienced 56.5 pregnancy-related deaths per 100,000 live births during 2020–2022—3.8 times the White rate and four times the Asian rate.
As a doula serving Los Angeles and San Bernardino Counties, I see faces behind those numbers. I remember concerns raised softly, then firmly, then desperately. I am tired of watching Black families enter spaces meant to protect them, only to discover they must defend themselves while laboring, bleeding, trembling, or recovering.
Returning to Client A
Client A’s labor stretched nearly 48 hours. As her condition worsened, she, her partner, and I asked whether a cesarean should happen sooner. A provider questioned my place as a doula, then said she was next.
Six more hours passed.
She entered surgery visibly ill with a serious uterine infection, her baby malpositioned and stuck. Her partner later recalled the provider saying, “This baby would never have made it through the birth canal.”
Those words landed like a blow. Our urgency had been treated as ignorance. With Client B, we questioned why surgery was inevitable. With Client A, why it was delayed. Doula advocacy is not about one kind of birth. It is about informed consent, individualized care, and timely action. Hospital routine should never outweigh the person carrying the risk.
Survival Cannot Be the Standard
The Black maternal health crisis includes unequal care, untreated conditions, racial bias, delayed referrals, poor communication, and inadequate postpartum support. It is about birth plans respected only until a hospital becomes less busy and postpartum care that asks whether a mother survived, not whether she has what she needs to recover.
Survival cannot be the standard. Technology can support care, but it cannot replace human connection. An algorithm cannot detect fear in a patient’s eyes, and a mission statement alone cannot ensure adequate staffing or culturally responsive care.
The Story of Client C
Before I arrived, I heard the chaos through Client C’s phone. Staff struggled to locate her baby’s heartbeat on an external monitor as her fear and blood pressure rose. I pleaded for an internal electrode before surgery.
“There’s not enough time,” a nurse said.
“I would like to wait for my doula,” Client C called out.
But she was medicated, hurried through consent, and wheeled away while I listened.
In the operating room, after a shift change, another nurse placed an internal electrode and said, “The previous monitor wasn’t working.”
No one responded.
According to her father, the obstetrician avoided eye contact: “We need to move forward.”
Surgery may still have been necessary; that was not mine to determine. But if faulty equipment helped create the emergency, the family deserved acknowledgment and explanation—not silence. No family should have to wonder whether major surgery followed an unavoidable crisis or a machine failure no one recognized in time.
From Prevention to Accountability
After supporting nearly 100 families, I have learned that danger often begins before admission. I have urged clients to seek care—and heard why they feared returning: dismissed pain, harsh words, shame for asking questions.
Care cannot be holistic where Black families do not feel safe enough to speak or return. Representation matters, but providers of color cannot repair inequity alone. They need adequate staffing, mentorship, culturally responsive training, reliable equipment, and colleagues that are reflective of all the aforementioned. It’s not the Black providers job to care for just the Black patients, everyone should have the same goal.
The Momnibus Act, California’s Medi-Cal doula benefit, the Transforming Maternal Health Model and the Perinatal Equity Initiative require more than promises; they need sustained funding, reliable reimbursement and accountable implementation.
Birth should be sacred. Yet too many Black birthing people arrive carrying the burden of proving their pain is real. A doula can listen, educate, comfort, and advocate—but cannot repair a system that refuses to listen. The true measure of progress is what happens when a Black birthing person says, “Something is wrong.”
Are they believed? When equipment fails, is that failure acknowledged? Do families leave not merely alive, but safe, respected, supported, and whole?
Until those answers are consistently yes, California’s maternal health success story remains unfinished.
About the Author
Antoinette Stewart-Eneh is a mother of two, holistic maternal wellness advocate, and birth and postpartum doula who has supported families since 2019. She serves as program operations coordinator for Frontline Doulas, a volunteer client coordinator with the Joy in Birthing Foundation and a childbirth educator in South Los Angeles. She is studying to become a midwife and lactation educator.
Black Press
New Protections for Ticket Buyers: Gov. Newsom Signs Assemblymember Isaac Bryan’s Bill
OAKLAND POST — Assembly Bill 1349 expands state regulation of original ticket sellers, resellers and online resale marketplaces. The law targets deceptive sales practices, ticket-buying software and speculative listings — tickets advertised for sale by sellers who do not possess them or have authorization to sell them.
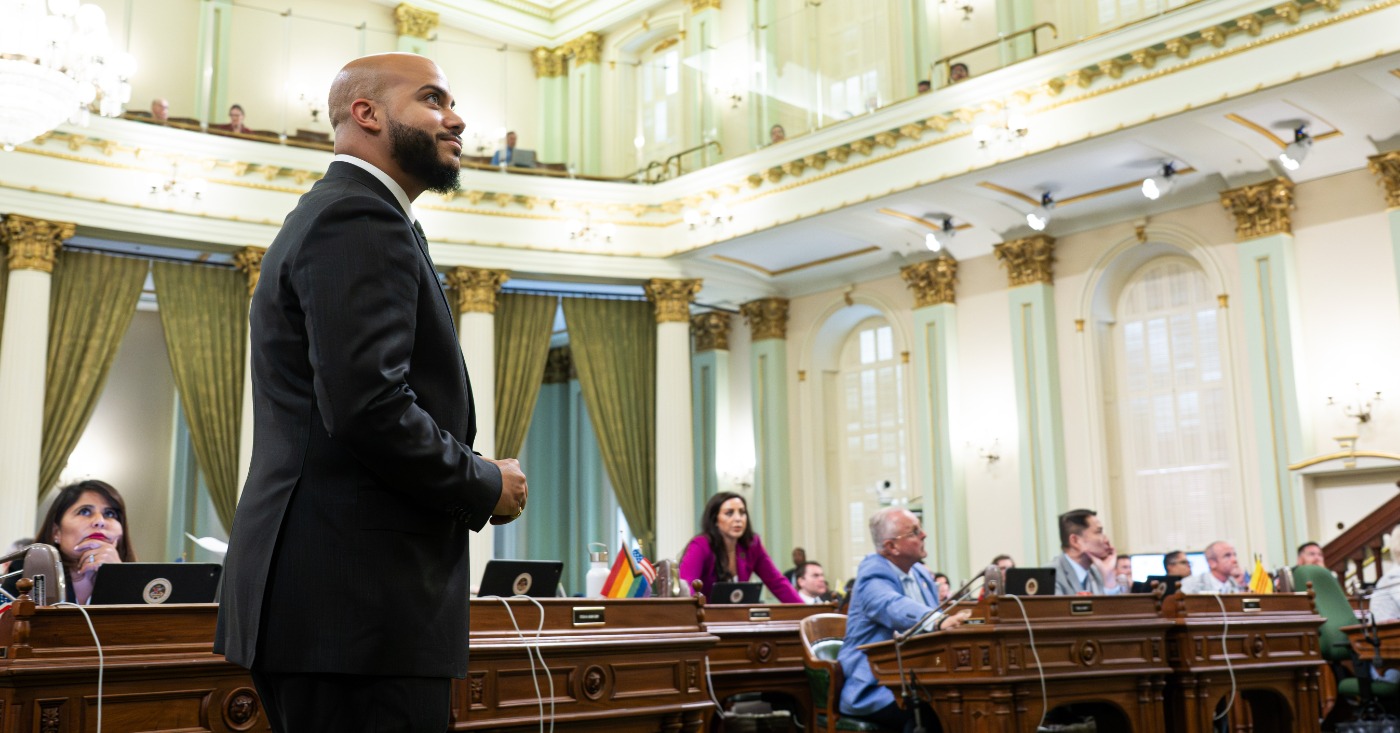
Gov. Gavin Newsom signed legislation on Sept. 27 authored by Assemblymember Isaac Bryan (D-Ladera Heights) that strengthens consumer protections for Californians purchasing tickets to concerts, sporting events and other live entertainment.
Assembly Bill 1349 expands state regulation of original ticket sellers, resellers and online resale marketplaces. The law targets deceptive sales practices, ticket-buying software and speculative listings — tickets advertised for sale by sellers who do not possess them or have authorization to sell them.
“Buying a ticket shouldn’t come with hidden risks or unfair practices,” Newsom wrote on social media after signing the measure.
Under AB 1349, ticket sellers are prohibited from listing tickets before they have been officially released unless they have authorization or a legally enforceable right to receive them. Online marketplaces must also take reasonable steps to prevent speculative ticket sales on their platforms.
The law prohibits sellers from using bots, multiple accounts, email addresses or internet protocol addresses to circumvent ticket limits, presale restrictions, electronic queues and other controls. It also bans websites and advertisements designed to mislead buyers into believing they are purchasing tickets from an authorized seller, venue or event organizer.
Sellers who violate certain provisions and fail to provide a promised ticket may be held liable for twice the ticket’s contracted price. Buyers may also recover nonrefundable expenses incurred while attempting to attend an event, along with reasonable attorney’s fees and court costs.
Pastor Tecoy Porter Sr., president of the National Action Network’s Sacramento chapter, said the law establishes needed accountability.
“Buying a ticket to a concert or show shouldn’t mean entering a marketplace where the rules are stacked against you. This year, we worked with a coalition of consumers, civil rights advocates, community groups, and businesses to make AB 1349 stronger. Consumers deserve enforceable rules that protect them. We thank Assemblymember Bryan for his leadership, and we will keep working to make ticketing fair for every Californian.”
Jose L. Barrera, national vice president for the Far West Region of the League of United Latin American Citizens, also praised the measure.
“Californian families deserve certain protections when they buy tickets. Assemblymember Bryan listened to communities across California and delivered a bill that puts fans first. We thank him and Governor Newsom for making it law.”
Black History
COMMENTARY: Battling Black Voter Distrust
HOUSTON DEFENDER — Black voters have long been a reliable base for the Democratic Party, but political strategists and voters indicate that years of inconsistent engagement and unfulfilled expectations have created a trust gap.
Black voters have been among the Democratic Party’s most dependable supporters for generations. But loyalty and trust are not the same thing.
With less than a month to go before the midterm elections, Black voters and political strategists say years of inconsistent engagement and unmet expectations have left some voters questioning whether the party has earned their continued support. The challenge now is bigger than winning votes. It’s convincing distrustful voters that staying politically engaged is worth it.

Communications strategist Ashley Etienne argues that Democrats have spent years taking one of their most reliable voting blocs for granted, creating a widening trust gap that threatens the party’s long-term prospects in Texas and nationally.
“Trust is the currency of persuasion,” she said. “We’re seeing distrust at an all-time high, especially with Black voters … distrust of the media, institutions, the Democratic Party, self-agreement. Campaigns don’t lose because they fail to talk to voters. They lose because they fail to listen.”
Etienne, who served as a senior adviser to Presidents Barack Obama and Joe Biden and communications director for Vice President Kamala Harris, said repairing that relationship requires something considerably more difficult than another campaign advertisement. It requires listening.
Black support remains strong, but not absolute
Recent polling suggests Democrats continue to hold a substantial advantage among Black voters heading into November, but that support isn’t universal.
A July 2026 Pew Research Center survey found 68% of Black registered voters said they would support the Democratic candidate for U.S. House in their district, compared with 8% who favored the Republican. Another 25% said they were either unsure or would support another candidate.

That uncertainty follows some erosion in Democratic support among Black voters in the 2024 presidential election. A Pew analysis of validated voters found 83% of Black voters supported Kamala Harris in 2024, compared with 92% who supported Joe Biden in 2020.
Pew found that shift was driven less by individual voters switching from one party to another than by differences in who turned out to vote.
The findings don’t suggest Black voters have abandoned Democrats. They do raise questions about whether longstanding party loyalty is enough to guarantee participation.
“We’ve been making that same argument decade after decade,” Etienne said. “Those are becoming less persuasive arguments.”
Why is trust disappearing?
The distrust isn’t necessarily about one candidate or one election. For some Black voters, frustration comes from feeling heavily courted during election season without seeing enough progress afterward on the issues affecting their daily lives.
Housing costs remain a concern. So do education, economic opportunity, neighborhood investment, and the cost of everyday necessities.
That creates a difficult dynamic for campaigns: Asking voters to participate in a political system that some believe has not delivered enough for them.
It also raises a separate question. What happens when frustration with political parties becomes disengagement from the political process altogether?
What happens when voters stay home?
The answer can become particularly consequential in local elections, where races can be decided by hundreds of votes rather than thousands.
Harris County Democratic Party Chair Traci Gibson has pointed to several 2024 judicial races decided by narrow margins. District judge candidate Elaine Palmer lost by 304 votes, while Jeralynn Manor lost by 647 votes.
Gibson also warned about voters who begin Harris County’s lengthy ballot but don’t finish it.
“If you go into these polls and you vote for the first five people and then you leave, that’s how we get Elaine Palmer losing by about 300 votes,” Gibson said.
The larger issue extends beyond any candidate or political party. Judges are elected. School boards make decisions affecting students and families. City and county officials determine how public dollars are spent. State lawmakers decide which bills become state law.
Those decisions are made regardless of how many eligible voters participate.
“We have to have strategies, we have to have plans, we have to have a mechanism in place for people to feel they are heard.”
Karla West
For voters distrustful of political parties or government institutions, political participation also doesn’t have to mean unquestioning loyalty to either party.
Voters can research candidates individually, compare their positions, attend or watch candidate forums and examine an incumbent’s record against previous campaign promises. They can also learn what the often-overlooked offices farther down the ballot actually control.
In that sense, distrust can become a reason for greater scrutiny rather than disengagement.
Candidates have work to do, too
Responsibility for rebuilding participation doesn’t fall solely on voters.
At a recent Third Ward town hall hosted by state Rep. Jolanda “Jo” Jones, Harris County Precinct 7 Constable James “Smokie” Phillips and Houston Black American Democrats, voters and political strategists called for more sustained campaign engagement.
“Investment drives outcomes. If you don’t invest in it, it doesn’t work,” Etienne said.
She argued that campaigns spend heavily on polling, consultants and advertising while directing too little money toward Black-led political infrastructure and organizations with established relationships in Black communities.
Shamier Bouie, chair of Houston Black American Democrats, said organizing cannot begin a few months before Election Day.
“It’s all about year-round organizing, and increased investment in Black voter outreach … more funding for Black-led organizations that have relationships, infrastructure, and experience in effectively engaging Black communities,” Bouie said.
The question of investment also surfaced in July when Democratic U.S. Senate candidate James Talarico pledged $25 million toward Black voter outreach. Some voters wanted specifics about where and how that money would be spent.
“We still need our kids, we still need our schools equitably funded,” said Augie Cahee, vice president of marketing web delivery at JPMorgan Chase & Co. “So, we want to know what you’re going to do with the money. Don’t stand up and tell me $25 million and you don’t have a plan.”
The exchange illustrated the larger trust problem: Voters aren’t simply asking candidates to talk to them. They want to know what happens after the conversation.
From distrust to accountability
Karla West, a precinct chair for downtown’s Precinct 16, said responsibility ultimately belongs on both sides.
“We fell asleep at the wheel,” West said of voter turnout.
But she also challenged political leaders.
“The Democratic Party did not say what they would do for you,” West said. “We haven’t heard a plan for years. I’m sick of it. We have to have strategies, we have to have plans, we have to have a mechanism in place for people to feel they are heard.”
Defender Reporter Tannistha Sinha contributed to this report.
Based on reporting by Houston Defender.
Black History
Why Black Artists Struggle to Sell Tours
HOUSTON DEFENDER — Recent industry reports and artist comments indicate that Black artists are struggling to sell concert tickets, highlighting a larger crisis in the touring business. This trend, dubbed “blue dot fever,” refers to empty seats at venues and has led to major touring acts canceling or postponing shows since spring 2026.
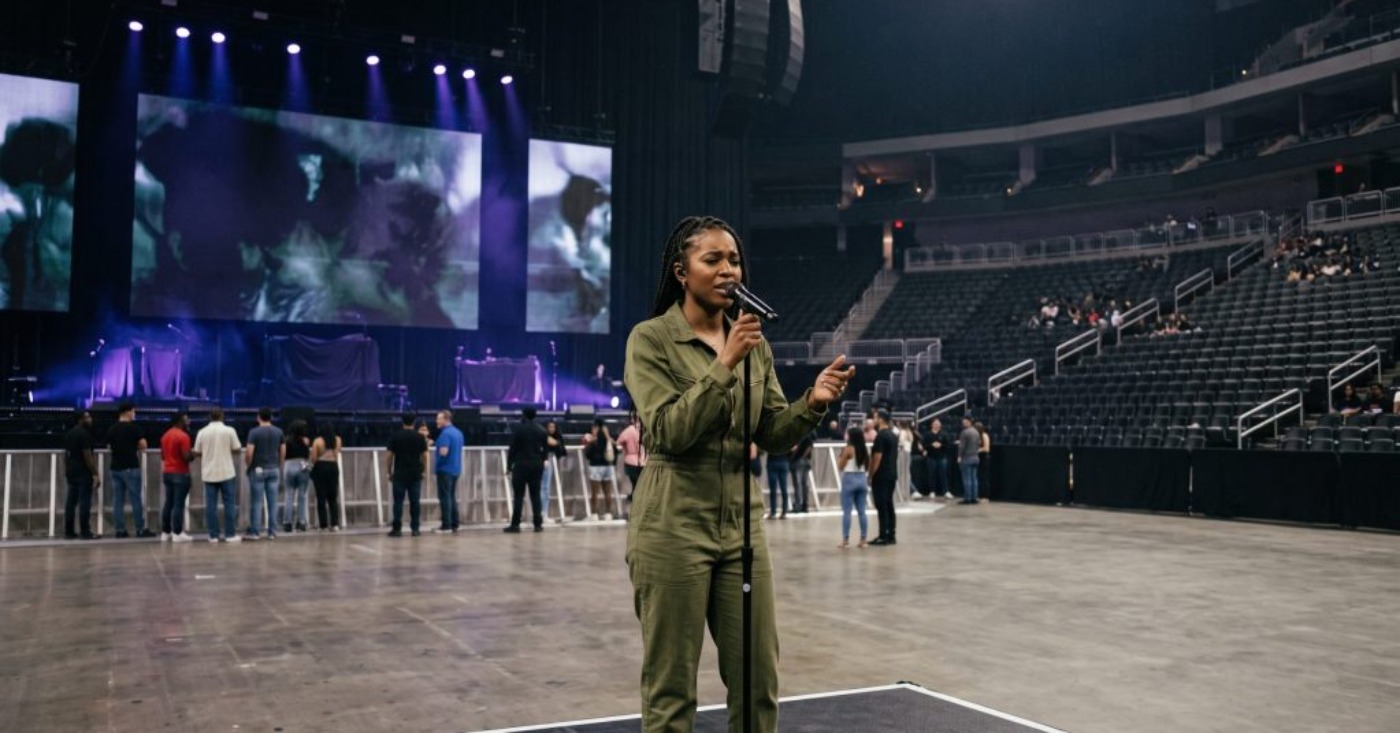
The internet chatter about Black artists struggling to sell concert tickets points to a much larger crisis reshaping the touring business, according to recent industry reporting and artists’ own comments.
Since spring 2026, a wave of major touring acts across genres have canceled or postponed shows due to sluggish ticket sales, a trend some in the industry have dubbed “blue dot fever,” a reference to the blue markers that indicate empty seats on Ticketmaster’s venue maps.
The phenomenon is not limited to Black performers, but several recent examples involving Black artists have fueled online conversation about whether Black touring acts face extra hurdles. For a market like Houston, home to a large hip-hop and R&B fan base and a steady stream of major tour stops, the debate carries added weight.
Here are five reasons the touring business has gotten tougher for artists trying to fill seats.
Blue dot fever is spreading industrywide
Black hip-hop megastars like Ludacris, T.I., Rick Ross, and BigXThaPlug felt the impact of Blue Dot Fever after struggling to sell tickets. Industry watchers say many artists are being booked into venues too large for their current draw, leaving sections visibly empty, discouraging last-minute buyers. The trend cuts across genres, but it has compounded challenges already facing some Black touring artists this year.
Fans keep comparing every artist to music’s biggest superstars
Grammy-winning singer Melanie Fiona recently weighed in on the online conversation about canceled shows and slow sales, explaining that most artists do not have the resources or reach of music’s top-tier headliners. The trade outlet Ticket News has made a similar point, noting that few artists can match the pricing structure or demand generated by superstar-level tours. When any artist falls short of that bar, fans and social media users are quick to call it a flop, even when the artist is still performing at a healthy level for their career stage.
Stadium bookings are outpacing actual demand
A hip-hop stadium concert set to take place in Louisville in October 2026, featuring Ludacris, T.I., Rick Ross, and BigXThaPlug, reportedly had nearly 47,000 seats still available as showtime approached. The example illustrates a broader booking problem. Venues sized for arena or stadium crowds do not always match the number of fans willing or able to buy tickets, regardless of an artist’s streaming numbers or name recognition. Some promoters are now facing pressure to book smaller, more intimate venues that better match an act’s current draw.
Rising costs are squeezing fans’ entertainment budgets
Housing, groceries, and everyday expenses have climbed for many households, and live music is often one of the first expenses fans cut. Older or legacy acts leaning on nostalgia appear to be hit hardest, since higher ticket and fee prices make attending a bigger financial decision than it once was. Newer or lower-profile Black artists competing for the same limited entertainment dollars face an uphill climb, especially when fans have to choose between one or two shows a year instead of several.
Social media shape who gets mainstream exposure
Does TikTok Dominate the music industry.
Black artists in hip-hop and R&B often compete for airplay and playlist placement within genre-specific categories rather than mainstream ones, which can limit the crossover exposure that turns streaming success into ticket sales. Artists working outside those two genres, including gospel, jazz, and Afrobeats-influenced acts, face a similar challenge in reaching audiences beyond their dedicated fan bases. Whether that structural gap is driving today’s sales slump remains an open question that industry analysts and artists are actively debating.
Based on reporting by Houston Defender.
Black Press
COMMENTARY: Property Is Power! What Is a Gift of Equity and What Could It Mean for Black America?
MICHIGAN CHRONICLE — For many Black families, a significant hurdle to homeownership is not the monthly mortgage payment, but rather the initial costs such as down payments, closing costs, and other cash requirements. This can delay homeownership for years, even for individuals with stable careers, good income, and reasonable credit.
For generations, the conversation about Black wealth has focused on what we do not have: not enough savings, not enough access to capital, not enough homeownership and not enough inherited wealth. Those realities matter, and the disparities behind them are real but there is another question worth asking: What are we doing with the wealth we already have?
That question deserves more attention because one of the greatest barriers to homeownership is often not the ability to make a monthly mortgage payment. It is the ability to get through the front door the down payment, closing costs and cash required to purchase a property in the first place. For many Black families, that initial hurdle can delay homeownership for years, even when someone has a stable career, good income, reasonable credit and the financial capacity to sustain a mortgage.
Yet in some families, part of the solution may already be sitting within the family itself.
Across Black America, there are parents, grandparents, sisters, brother, aunt and uncles who may not consider themselves wealthy but who own something extraordinarily valuable equity. They purchased homes decades ago, made mortgage payments month after month, raised families in those homes, maintained them through recessions and difficult economic periods and, over time, watched those properties appreciate. A house purchased for $50,000 or $75,000 may today be worth $250,000, $300,000 or considerably more.
That difference represents more than appreciation on a financial statement. It represents years of work and sacrifice converted into an asset and therein lies a tremendous opportunity.
A gift of equity allows a homeowner, typically in a transaction involving family, to sell a property for less than its appraised market value and transfer some of the difference to the buyer as equity. Subject to the requirements of the mortgage program, that equity can potentially be used toward the buyer’s down payment and, in some circumstances, closing costs.
Example. Suppose a mother owns a home that appraises for $300,000. She wants to sell it to her daughter for $240,000. The $60,000 difference between the appraised value and the sales price can potentially become a gift of equity. The mother does not have to withdraw $60,000 from a bank account and hand it to her daughter. The wealth is already there it has been accumulating inside the property.
That is what makes this strategy so important to understand. We frequently talk about the difficulty of saving a down payment without asking whether a family may already possess an asset capable of helping overcome that barrier. A son or daughter could spend another five or ten years attempting to save enough money to purchase a home while a parent or grandparent is sitting on substantial equity accumulated over several decades.
The family has wealth it simply may not be liquid.
A gift of equity can create a bridge between those two realities. The previous generation may have spent 30 years building equity so that the next generation does not have to begin at zero. That is one of the deeper meanings of generational wealth. It is not simply about leaving something behind after we die. It is about understanding whether the assets one generation has built can improve the economic starting position of the generation that follows.
For Black families, that distinction is especially important we have spent generations fighting for access to property and the opportunity to own it. As more Black families acquire homes and build equity, the conversation must eventually expand beyond the question of how we create more first-generation homeowners. We must also ask how the ownership already achieved by one generation can help create ownership in the next.
This requires us to think differently about inheritance. We often imagine inheritance as an event that occurs at the end of someone’s life, when assets pass through a will, trust or estate. But property gives families another possibility. Under the right circumstances, real estate can be used to transfer economic opportunities while parents and grandparents are still alive to participate in the process and see what the asset they spent decades building can do for the next generation.
A parent may not have $100,000 sitting in a savings account that does not mean the parent has nothing substantial to give. The family home may be the largest asset that person owns, and this points to a distinction that is essential to any serious conversation about wealth income is what we earn; wealth is what we own.
A family can have relatively modest income and still possess meaningful wealth because a home purchased decades earlier has appreciated while its mortgage has steadily been paid down. This matters for Black America because the racial wealth gap cannot be understood solely as a question of wages and income. It is also a question of ownership, assets and whether those assets successfully move from one generation to another.
Return to the mother with the $300,000 home. She could sell the property on the open market, receive the proceeds and allow the house to leave the family. There is nothing inherently wrong with that decision. She earned that equity, and her own financial security must matter. But suppose her circumstances allow another choice. She sells the property to her daughter for $240,000 and provides $60,000 through a gift of equity.
Her daughter may now be able to purchase a home she otherwise could not have acquired because she lacked sufficient cash. More importantly, she does not necessarily begin her ownership journey at zero. She enters it with equity. If she manages the property responsibly, makes the mortgage payments, maintains the home and allows time and amortization to work, the economic value accumulated by one generation has the potential to continue growing in another.
The mother has therefore transferred more than a house she has transferred a financial head start.
That is when property becomes more than shelter it becomes capital.
None of this means that a gift of equity eliminates financial responsibility or the normal requirements of obtaining a mortgage. The buyer still has to qualify. A lender will evaluate credit, income, debt and the ability to repay the loan. The property generally must be appraised, title requirements must be satisfied and the transaction must comply with the rules of the mortgage program.
There is documentation as well. A lender will generally require a gift-of-equity letter identifying the parties, their relationship, the amount of the gift and confirmation that repayment is not expected. That final requirement matters because a gift cannot secretly be another loan. If a parent provides $50,000 in equity but expects the child to repay the $50,000 later, it is not a true gift for mortgage purposes.
The larger issue, however, is not the paperwork. It is what happens to Black-owned property over time. For much of American history, Black families faced enormous barriers to acquiring property in the first place. Redlining, restrictive covenants, discriminatory lending and unequal access to mortgage credit limited where Black Americans could purchase homes and whether they could obtain the financing necessary to do so. Against that history, when a Black family has managed to acquire property, pay for it, preserve it and accumulate substantial equity over decades, we should understand what has been created.
It is not simply a house it is an asset, and assets require strategy.
Before a family property is simply listed for sale, there should be a deeper conversation around the kitchen table. What is the property actually worth? How much equity has accumulated? Is there someone in the next generation who wants the home and is financially capable of maintaining it? Could that person qualify for financing? Could a gift of equity help make the transaction possible? And perhaps most importantly, what do we want this asset to accomplish for our family?
Generational wealth rarely happens by accident. Someone has to think beyond today’s transaction and understand that the equity accumulated over 20, 30 or 40 years represents stored economic power.
A gift of equity will not be appropriate for every family, and it is certainly not a solution by itself to the racial wealth gap. But it illustrates a much larger principle. We should not spend all of our time discussing the wealth Black America has yet to build while overlooking the wealth that millions of Black families have already spent generations creating.
That is what it means to turn ownership into legacy.
Property is Power. And when property passes from one generation to the next with knowledge, planning and purpose, that power can outlive us.
Property is Power! is a movement to promote home and community ownership. Studies indicate homeownership leads to higher graduation rates, family wealth, and community involvement.
Based on reporting by Michigan Chronicle.
Auto
Consumers and States Awarded $694 Million After Predatory Auto Lender Settles Lawsuit
WASHINGTON INFORMER — A class-action settlement involving predatory auto lender Credit Acceptance Corporation (CAC) has resulted in $694 million in relief for an estimated 55,000 consumers. Attorneys general from 40 states and the District of Columbia announced the settlement with one of the nation’s largest subprime auto lenders on September 18.
An estimated 55,000 consumers will benefit from a $694 million class-action settlement against a predatory auto lender reached by attorneys general in 40 states and the District of Columbia.
The settlement announced on Sept. 18 with Credit Acceptance Corporation (CAC), one of the nation’s largest subprime auto lenders, will provide the following financial relief for affected consumers:
- $630 million in debt relief for consumers — $388 million to consumers whose cars have been repossessed; the remaining $246 million for those whose vehicles have not been repossessed and will now keep their autos.
- $60 million in restitution to thousands of additional consumers who were misled and lost their cars within months of taking out their loans.
- $15.5 million in reimbursement to each state office that comprised the multistate working group, and the National Association of Attorneys General.
“CAC preyed on consumers in New York and across the nation with false promises of affordable loans, only to exploit them with outrageous interest rates that ruined their credit and cost them their cars,” said New York Attorney General Letitia James, who led the multi-state effort. “While their customers struggled to make payments, CAC made millions. By continuing our case to hold CAC accountable, we secured hundreds of millions of dollars in debt relief and restitution for all those who were taken advantage of by their schemes.”
The lawsuit, originally filed in 2023, alleged that CAC projected, down to the penny, how much money it could extract from borrowers through loan payments, late fees, repossession and auction, debt collection, and wage garnishment, without considering a consumer’s ability to repay their loan, according to James. CAC then offered to split the projected collections with its affiliated dealers.
Low-income borrowers with either low credit scores or little credit history were routinely pushed into purchasing vehicles that were worth far less than their loans. CAC states on its own website: “Approval decisions are typically available in 30 seconds or less, and nearly 80 percent of deals are approved for funding within 24 hours.”
Further, CAC misstated key terms on loan agreements, including the principal and interest amounts, and did not disclose thousands of dollars in credit charges. Although the average loan carried an annual interest rate of more than 38%, other rates reached over 100%. These predatory debt trap loans soon defaulted within 12 or 18 months.
“Credit Acceptance Corporation set car buyers up to fail by making loans it knew they would never be able to afford, and by allowing dealers to inflate the cost of financing agreements with hidden add-ons. As a result, the company profited, even while customers lost their cars and continued to struggle with debt,” said District of Columbia Attorney General Brian L. Schwalb.
Other state officials had similar reactions to the settlement.
“Credit Acceptance Corporation closed its eyes to deceptive origination practices and made predatory, high-cost auto loans that were likely to result in repossession and leave consumers trapped in a cycle of debt,” said California Attorney General Rob Bonta.
Consumers eligible for restitution will be notified by a claims administrator. Consumers with questions about the settlement can call CAC’s customer service number at 800-634-1506.
The settlement also provides additional terms that will free affected consumers from many of the other financial harms inflicted, while other stipulations carry long-term, consumer-friendly reforms.
In the short term, CAC must contact and clearly inform consumers of any products they purchased and offer them a process to cancel those products while keeping their vehicles. It must also notify all affected consumers that their car loan accounts have been closed, no further payments are owed, any lien held has been released, and the certificate of title has been sent. Credit bureaus will also be notified of these actions.
For the next five years, CAC is required to submit written reports that demonstrate how it is complying with all aspects of the consent order. Any failure or shortcomings related to the order will prompt a mandatory remediation plan with details that identify how compliance will be achieved.
Other long-term settlement stipulations that CAC must observe:
- Providing consumers with pre-loan disclosures about the risks of default and the value of the vehicle.
- Limiting a price cap for vehicle prices to no more than 109% of retail book value for certain consumers.
- Implementing procedures that prevent dealers from raising car prices due to creditworthiness or above advertised prices.
Comments in a report released earlier this year by the Center for Responsible Lending showed how consumers with subprime credit scores, most of whom are Black, were left reeling from the effects of predatory car loans.
As Nicole, one participating consumer, noted, “You pay that and nothing, nothing ever changes.”
As CAC faces court-ordered reforms and restitution, Nicole and similar consumers can finally receive well-earned financial fairness.
Charlene Crowell is a senior fellow with the Center for Responsible Lending. She can be reached at[email protected].
Based on reporting by Washington Informer.

Listening as a Lifeline: A Doula’s Witness to Black Maternal Health

New Protections for Ticket Buyers: Gov. Newsom Signs Assemblymember Isaac Bryan’s Bill

‘We Don’t Talk Trash — We Pick Up Trash!’

Zakiya Jendayi Arrested, Locked Out of Home by Sheriff’s Deputies

2027 Chevy Bolt EV: Is It Worth Under $30K? #shorts

Leading the Way in HBCU Research

Smooth Ride! Car Suspension & Comfort Tested #shorts

61 years since Selma, Houston leaders say the bridge remains to be crossed
Here is what you need to know about finding unique white elephant gift ideas that everyone wants to steal
Check out these proven ways to increase property value for commercial business locations

Latest Massacre in Haiti Reveals Cruelty U.S. Deportations

Black Americans Have Doubts About the U.S. Food System

When Praises Go Up: SUGC Nominated for Prestigious Stellar Award.

Booked and Unbound: The Legacy of Black Women’s Literary Circles

U.S. Sole Nation to Oppose U.N. Resolution Correcting Africa’s Size on World Maps

The Youngest American Killed in the Vietnam War

COMMENTARY: Big Mama Said ‘Don’t Let Grief Break the Bank’

U.S. Open Influencers Spark Backlash over Ring Lights, Filming as Gauff and Osaka Speak Out

Prostate Cancer is Twice as Likely to Kill Black Men. Talking to Your Doctor Could Help Save Your Life

Outnumbered: Elbert Cox’s Equation for Greatness
2027 Chevy Bolt EV: Is It Worth Under $30K? #shorts
Leading the Way in HBCU Research
Smooth Ride! Car Suspension & Comfort Tested #shorts
61 years since Selma, Houston leaders say the bridge remains to be crossed

Lutheran North Celebrates Homecoming With 40 to 19 Win Over Westminster Christian

Luxury Car Features: Harman Kardon & More! #shorts

Tuskegee Airmen Field Reopens in The Ville, Giving St. Louis Youth a Place to Grow

2027 Chevy Bolt: Worth $29,990? Hidden Flaws Revealed! #shorts

Kia Seltos Luxury Car Tech: Prestige Package Features Explained! #shorts

Serena Williams: The Beast Narrative & Black Womanhood #shorts
-
 Black History1 week ago
Remembering Chauncey Bailey as Student Journalists Face Threats to Truth-Telling
-
 Black Press4 days ago
OP-ED: Haiti TPS: Have We Lost Sense of Humanity?
-
 Black Press1 week ago
Poll: Becerra Widens His Lead Over Hilton; Californians Split on Wealth Tax
-
 Black History7 days ago
COMMENTARY: The Audacity of Joyce Beatty
-
 Black History6 days ago
Rulings Leave Questions Lingering in Nolan Wells Case
-
 Black History6 days ago
Baptist Minister Says Black Church Champions for Civil Rights to Reign but Hesitates to Let Black Women Lead
